
Estimate Your Cash-Out Refinance Loan and Net Proceeds
A calculator for cash out refinance estimates how much equity you may be able to access, your new mortgage amount, and the cash you could receive after costs.
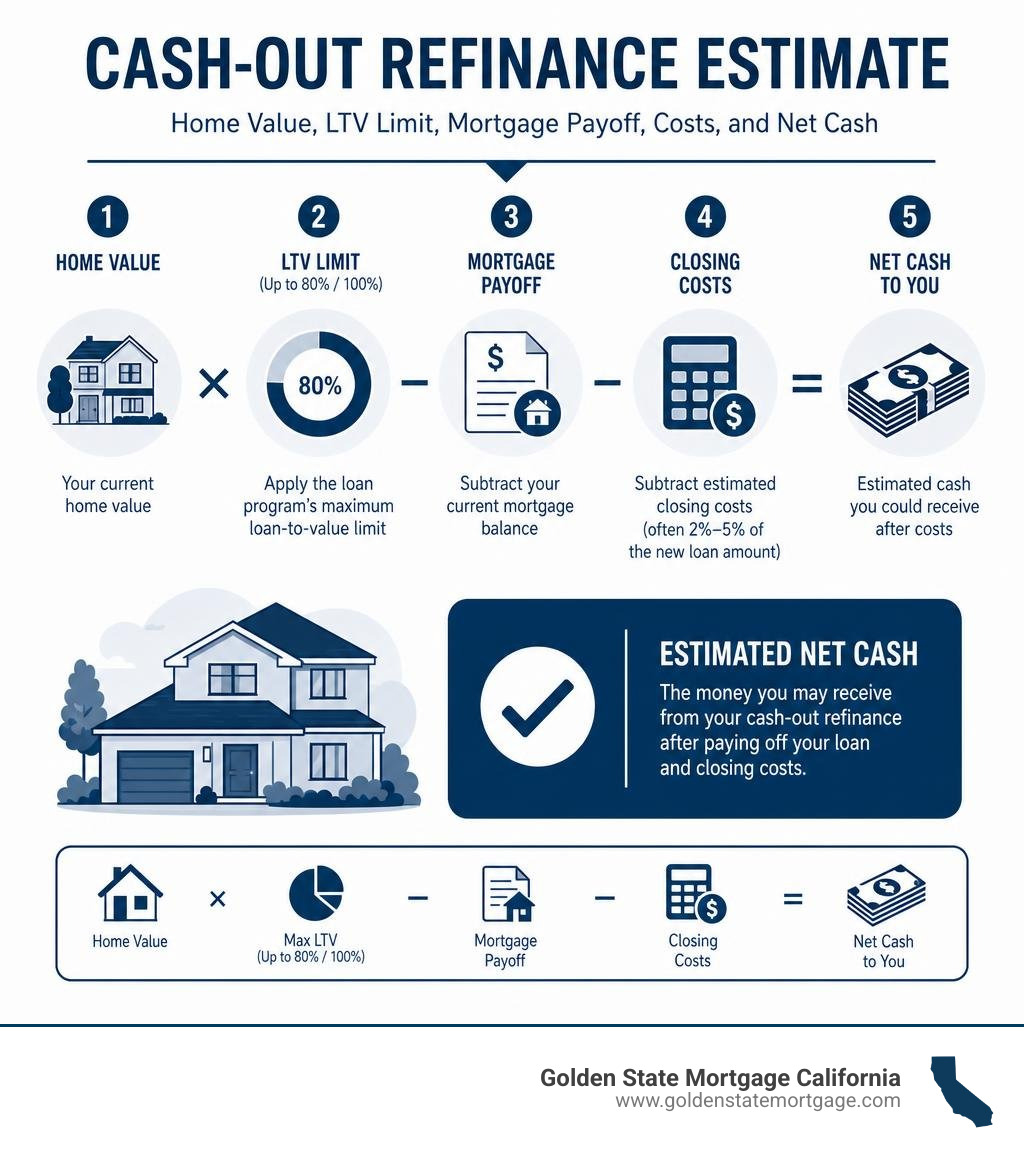
- Start with your current home value.
- Apply the loan program’s maximum loan-to-value limit. Conventional and FHA cash-out loans are commonly capped at 80% LTV, while eligible VA borrowers may have options up to 100% LTV.
- Subtract your current mortgage payoff balance.
- Subtract estimated closing costs, which often range from 2% to 5% of the new loan amount.
Quick formula:
Estimated net cash = (Home value x maximum LTV) – current mortgage balance – closing costs
The result is an estimate, not a loan approval. Your appraisal, credit, debt-to-income ratio, loan type, and final lender fees can all change the amount available. A cash-out refinance replaces your existing mortgage with a larger new loan, so it is important to look beyond the cash at closing and consider the new rate, payment, and loan term.
I am Dale Gremillion, a Senior Loan Officer and Producing Branch Manager with more than 25 years of residential lending experience across conventional, FHA, VA, jumbo, and other mortgage programs. I use the same core inputs in a calculator for cash out refinance to help California homeowners compare their equity options with clarity before moving forward.
How a Calculator for Cash Out Refinance Works
Understanding the math behind a calculator for cash out refinance gives you total clarity over your real estate wealth. When home prices rise in markets from Los Angeles to Sacramento, your equity grows right alongside them. A cash-out refinance lets you access that built-up wealth by replacing your current home loan with a completely new, larger primary mortgage. You pay off your existing loan balance, cover the necessary closing fees, and take the remaining funds home as cash.
To determine how much cash you can actually pocket, the calculator processes a few fundamental financial metrics:
- Appraised Home Value: What your property would sell for in the current real estate market.
- Loan-to-Value (LTV) Cap: The maximum percentage of your home’s value that a lender will allow you to borrow against.
- Current Mortgage Payoff: The total principal balance required to fully satisfy your active home loan.
- Refinance Closing Costs: Third-party and lender fees associated with originating the new mortgage.
The net cash payout formula follows a straightforward path:
- Maximum Loan Amount = Appraised Home Value × Maximum LTV Limit
- Gross Cash Available = Maximum Loan Amount – Existing Mortgage Payoff Balance
- Net Proceeds in Your Hand = Gross Cash Available – Estimated Closing Costs
For instance, if your property in San Diego appraises for $800,000 and you qualify for an 80% LTV conventional cash-out loan, your maximum new mortgage amount is $640,000 ($800,000 × 0.80). If you currently owe $400,000 on your home, your gross cash limit is $240,000. After deducting estimated closing costs of roughly $12,000 (3% of the new loan amount), your net proceeds come out to approximately $228,000.
For quick side-by-side estimates, tools like the Cash-Out Refinance Calculator — Net Cash + Breakeven — CalcBold demonstrate how even small changes in interest rates or LTV caps shift your cash at closing and monthly breakeven timeline.
Inputs Needed for a Calculator for Cash Out Refinance
To get an accurate result, you need to plug precise numbers into the calculator. If you put vague guesses into financial tools, you get vague figures back out. Here are the exact data points you should gather:
- Current Home Value Estimate: Look at recent sales of comparable properties in your immediate California neighborhood, or use an Automated Valuation Model (AVM) estimate. That a formal appraisal will establish the official number during underwriting.
- Outstanding Mortgage Balance: Check your latest monthly mortgage statement for your exact payoff balance (which is slightly higher than your principal balance due to accrued daily interest).
- Estimated Interest Rate: Cash-out refinance rates carry a minor rate premium—typically 0.25% to 0.50% higher than standard rate-and-term refinances—due to Fannie Mae Loan-Level Price Adjustments (LLPAs) and overall risk pricing.
- New Loan Term: Decide whether you are choosing a standard 30-year fixed term, a 15-year term, or an adjustable-rate product.
- Property Taxes, Hazard Insurance, and HOA Fees: Calculating full housing commitments requires tracking your true PITI payment (Principal, Interest, Taxes, and Insurance). For example, if you own property in higher-tax areas, that annual liability gets divided into your monthly escrow escrow allocation, impacting your overall Debt-to-Income (DTI) ratio.
How LTV Caps Limit Borrowing Capacity
LTV constraints act as the firmest boundary when pulling money out of your property. Lenders establish strict risk limits depending on the mortgage program backing your loan:
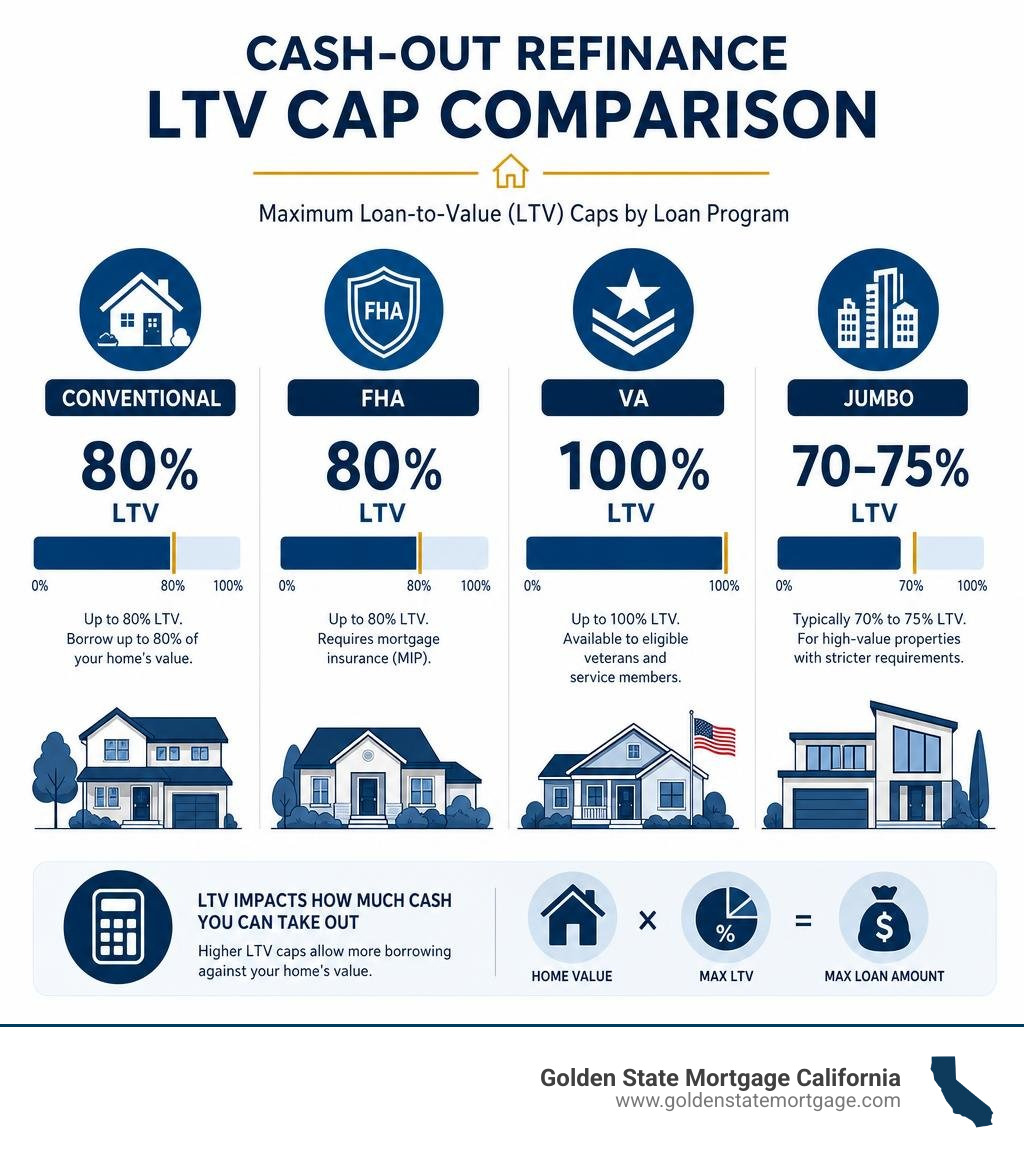
- Conventional Loans (Fannie Mae / Freddie Mac): Most conventional cash-out refinances on primary residences cap maximum LTV at 80%. This ensures you retain at least 20% equity in the property, eliminating the need for private mortgage insurance (PMI).
- FHA Cash-Out Refinances: Federal Housing Administration (FHA) cash-out refinances are also capped at 80% LTV (a policy shift lowered this ceiling from 85% back in April 2019). FHA cash-out loans require upfront and annual Mortgage Insurance Premiums (MIP) regardless of LTV.
- VA Cash-Out Refinances: Available to qualified active-duty service members, veterans, and eligible surviving spouses, VA cash-out refinances allow up to 100% LTV on primary residences. This makes the VA loan the most generous equity extraction tool on the market, though funding fees apply.
- Jumbo Loan Cash-Outs: For high-value properties in premium California markets like San Francisco, San Jose, or Irvine, jumbo cash-out loans often enforce tighter LTV caps (typically 70% to 75% LTV), alongside stricter credit score and cash reserve requirements.
Cash-Out Refinance vs. Rate-and-Term Refinance and HELOC
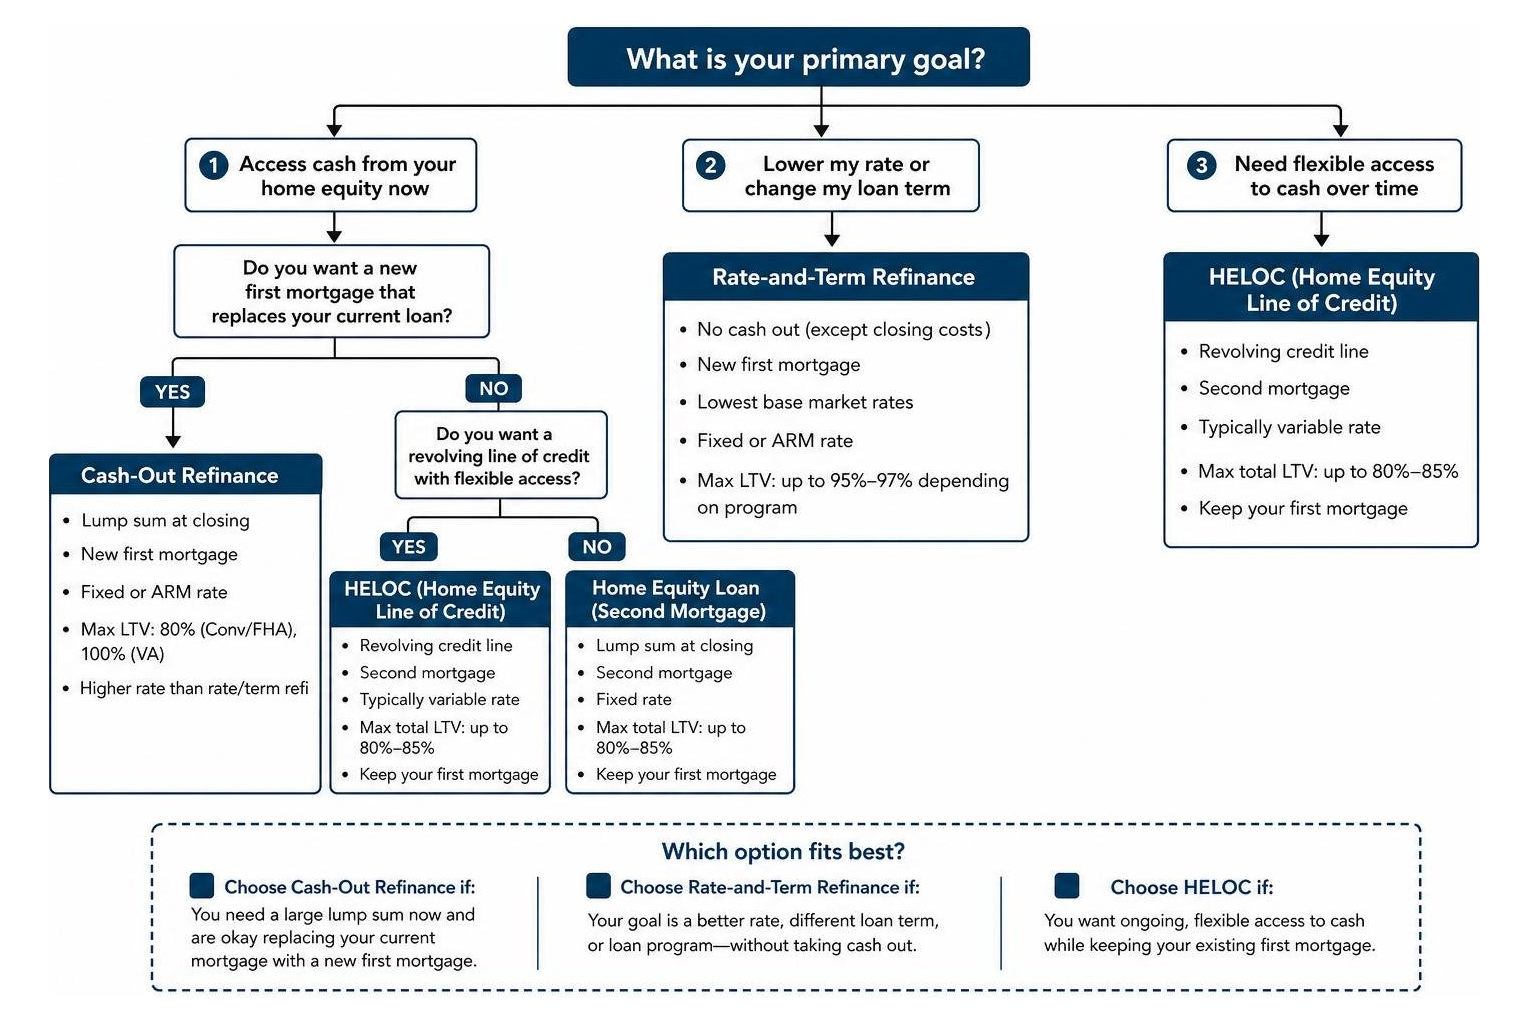
Homeowners tapping into their home equity often weigh three main loan structures: a cash-out refinance, a rate-and-term refinance, and a Home Equity Line of Credit (HELOC). Each serves a distinct financial purpose, and selecting the wrong tool can lead to unnecessary costs.
A rate-and-term refinance strictly changes your mortgage’s interest rate, loan length, or loan program (such as switching from an ARM to a fixed rate) without giving you extra cash payout at closing. The loan balance only increases to wrap in closing costs.
A HELOC acts like a second mortgage on top of your existing primary loan. It gives you a revolving credit line secured by your home equity. HELOCs usually carry variable interest rates and allow you to borrow, repay, and re-borrow money as needed during an initial draw period (typically 10 years).
A Home Equity Loan is another second-mortgage option that delivers a single, fixed-rate lump sum without disturbing your first mortgage.
Here is how these options stack up side by side:
| Feature | Cash-Out Refinance | Rate-and-Term Refinance | HELOC (Home Equity Line of Credit) |
|---|---|---|---|
| Primary Goal | Access equity + replace existing loan | Lower rate or change loan term | Flexible, revolving access to cash |
| Mortgage Position | New First Mortgage | New First Mortgage | Second Mortgage (behind primary) |
| Maximum LTV | 80% (Conventional/FHA), 100% (VA) | Up to 95%-97% depending on program | Up to 80%-85% total combined LTV |
| Interest Rate Type | Fixed or ARM (Single rate) | Fixed or ARM (Single rate) | Typically Variable (Prime + margin) |
| Rate Premium | 0.25% to 0.50% above rate/term refi | Lowest base market rates | Starts higher; subject to rate hikes |
| Impact on First Mortgage | Replaces existing lower rate completely | Replaces existing rate completely | Keeps original low first mortgage rate intact |
Evaluating Your Results from a Calculator for Cash Out Refinance
Running your numbers through a calculator for cash out refinance is only step one. The real financial insight comes when you evaluate how your monthly household cash flow and total interest liability shift over time.
If you locked in an ultra-low 3% interest rate several years ago and primary mortgage rates today sit higher, executing a cash-out refinance means replacing that whole primary mortgage balance at today’s rate. That decision could raise your monthly payment significantly, turning your cash-out proceeds into expensive funding. In that scenario, leaving your low-rate primary mortgage untouched and securing a separate HELOC or second mortgage might save you thousands of dollars annually.
Conversely, if current interest rates match or sit lower than your active loan rate, or if you are consolidating 18% to 24% credit card debt into a single 6.5% mortgage, a cash-out refinance can dramatically trim your total monthly obligations.
To explore loan dynamics and run custom scenarios, visit our comprehensive Mortgage Education resources or consult our overview of available home loan solutions on our main site at Golden State Mortgage California.
Key Costs, Taxes, and Breakeven Calculations
Refinancing a mortgage isn’t free. Understanding the true transaction cost of extracting home equity helps you avoid frustrating surprises at the closing table.
Refinance closing costs typically run between 2% and 5% of the new total loan amount (or roughly 1% to 3% in upfront lender fees depending on loan size). On a $500,000 cash-out loan balance, closing costs generally range from $10,000 to $25,000. These costs include:
- Lender origination and processing fees
- Home appraisal fees
- Title search and title insurance premiums
- Escrow, closing, and recording fees
- Prepaid property taxes and homeowners insurance funding
You can choose to pay these costs out of pocket at settlement or roll them directly into your new principal balance, which reduces your net cash proceeds.
To see how these costs filter into your net payouts, you can run detailed modeling tools like the Cash-Out Refinance Calculator · Free (2026) · Toolita, which calculates net cash proceeds alongside long-term cost comparisons.
Calculating your breakeven point is crucial when your cash-out refi lowers your overall monthly costs (for instance, when consolidating higher-interest debts).
$$\text{Breakeven Point (Months)} = \frac{\text{Total Refinance Closing Costs}}{\text{Net Monthly Savings}}$$
For example, if your closing costs equal $6,000 and the transaction lowers your net monthly debt outflow by $300 across all accounts, your breakeven point is 20 months ($6,000 ÷ $300). If you plan to remain in your home longer than 20 months, the transaction makes financial sense. However, if your cash-out refinance increases your overall monthly payment and delivers no net monthly savings, your mathematical breakeven point is infinite—meaning the deal must be justified strictly by the long-term return on how you deploy the cash proceeds.
When it comes to taxes, tax deductions on cash-out funds have strict ground rules under federal law. According to IRS Publication 936, interest on cash-out refinance proceeds is only tax-deductible if the extra funds are used to buy, build, or substantially improve the qualified home securing the loan.
If you extract $75,000 to add a new bedroom or remodel a kitchen, that interest remains deductible up to federal mortgage debt limits. However, if you use that $75,000 to pay off credit cards, purchase a vehicle, or cover tuition, the interest paid on that cash-out portion is not tax-deductible. Always consult a qualified tax professional to review your specific situation.
Term Resets and Long-Term Amortization Costs
One often overlooked risk of a cash-out refinance is resetting your loan term. If you are 7 years into a 30-year fixed mortgage and refinance into a brand-new 30-year term, you stretch your debt horizon back out to 360 months.
Even if your new interest rate is identical to your old one, resetting the amortization clock shifts your early monthly payments heavily back toward interest rather than principal repayment.
On a standard 30-year mortgage at a 6.5% interest rate, the “flip point”—the point in time when your monthly payment finally shifts to paying more principal than interest—doesn’t occur until around Year 20.
Consider the lifetime cost impact: on a $400,000 loan at 6.5% over 30 years, total interest payments reach approximately $510,178. If you restart that loan term late in the game without paying extra principal, you add years of extra interest charges to your balance.
If you reset your term, consider making voluntary extra principal payments to keep your payoff timeline on track. For instance, making an additional $200 monthly principal payment on a $400,000 30-year loan at 6.5% can save roughly $103,000 in lifetime interest and cut nearly 5 years off your loan term.
Smart Strategies and Common Pitfalls to Avoid
Because your primary residence backs a cash-out refinance, how you use the proceeds matters. Tapping your home equity converts unsecured financial obligations or capital assets into debt tied directly to your shelter.
Industry-Recognized Best Uses for Cash-Out Equity
- Value-Adding Home Improvements: Remodeling kitchens, upgrading roof systems, or adding living square footage builds equity right back into your property while potentially qualifying for IRS tax deductions.
- High-Interest Debt Consolidation: Eliminating high-interest credit card debt (often carrying 18% to 29% APR) or high-rate personal loans by consolidating them into a lower mortgage rate can save hundreds of dollars each month.
- Real Estate or Strategic Investments: Deploying home equity into high-yield financial opportunities or primary property upgrades can work out well when your net investment returns comfortably exceed your effective mortgage interest rate.
Uses That Require Extreme Caution
- Funding Discretionary Spending: Using home equity for luxury vacations, expensive consumer goods, or short-lived discretionary expenses eats away at your hard-earned real estate wealth.
- Speculative Investments: Borrowing against your home to buy volatile assets or fund speculative business startups puts your roof at unnecessary risk.
To review options that fit your personal homeownership goals, explore our full catalog of mortgage solutions on our Mortgage Programs guide.
Mistakes When Estimating Equity Proceeds
Avoid these four common missteps homeowners make when modeling cash-out refinance scenarios:
- Relying on Aspirational Valuations: Using overly optimistic sales estimates instead of realistic market comps overstates your borrowing capacity. A formal appraisal sets the true standard.
- Ignoring Closing Costs in Calculation: Estimating cash out based on raw equity without accounting for 2% to 5% in closing fees leads to cash shortages at funding.
- Over-Borrowing Equity: Stripping out all accessible equity leaves you vulnerable if regional housing markets experience a temporary correction. Maintaining a buffer above minimum LTV limits protects your financial health.
- Consolidating Debt Without Fixing Habits: Converting unsecured credit card debt into a mortgage clears your card balances. But if spending habits don’t change, running up those credit cards again leaves you with high card balances and a much higher monthly mortgage payment.
If you are exploring alternative purchase programs or home buyer assistance options across California, read our breakdown on how to secure assistance grants through our guide to Everything you need to secure a $25,000 grant to buy a house.
Frequently Asked Questions About Cash-Out Refinances
Is the cash received from a cash-out refinance taxable?
No, the lump sum cash you receive at closing from a cash-out refinance is not considered taxable income by the IRS or the State of California. Because the funds represent borrowed money that you are contractually obligated to pay back over time, equity proceeds are not treated as earned income or capital gains.
However, as outlined in IRS Pub 936, whether the interest you pay on those cash-out funds is tax-deductible depends entirely on how you spend the cash. It is only deductible if used to buy, build, or substantially improve your home.
What is the maximum LTV allowed for a cash-out refinance?
Maximum Loan-to-Value limits are set by the agency or loan program underwriting your mortgage:
- Conventional Loans: Capped at 80% LTV on primary residences.
- FHA Loans: Capped at 80% LTV on primary residences.
- VA Loans: Allowed up to 100% LTV for qualified veterans and military borrowers.
- Jumbo Loans: Generally capped at 70% to 75% LTV depending on loan size, credit profile, and lender guidelines.
How do closing costs affect the net cash proceeds I receive?
Refinance closing costs directly reduce the final cash payout you receive at closing. Because closing costs typically range between 2% and 5% of the total new loan balance, those charges are deducted from your gross loan proceeds before the title company wires your remaining funds.
For example, if your gross loan calculation grants $100,000 in available cash, but loan origination, title, appraisal, and escrow fees total $7,000, your final net cash proceeds delivered to your bank account will equal $93,000. Alternatively, paying closing costs out-of-pocket preserves your full $100,000 payout.
Conclusion
A calculator for cash out refinance gives you a clear starting point for evaluating your home equity, potential net proceeds, and updated monthly payments. By looking closely at LTV limits, closing costs, term resets, and breakeven timelines, you can make confident, practical choices about your home’s equity.
Whether you are looking to renovate your home in Fresno, consolidate high-interest debts in Riverside, or evaluate jumbo refinance options in Los Angeles, working with an experienced mortgage team ensures your transaction is handled with care.
At Golden State Mortgage California, we guide homeowners across the state through every phase of home financing—delivering low rates, competitive fees, and personalized, end-to-end support seven days a week.
Ready to see how much equity you can unlock? Contact our expert team today to run your custom numbers, or visit our main page to learn more: Explore home loan solutions with Golden State Mortgage. You can also check out our latest market insights on our Blog to stay informed on current interest rate trends.


