
What Is the $25,000 Down Payment Grant and Is It Available?
When people talk about the $25,000 grant to buy a house, they are usually referring to a specific federal legislative proposal known as the Downpayment Toward Equity Act. This proposed legislation aims to provide direct cash grants at closing to help eligible first-time and first-generation homebuyers cover critical upfront costs, including down payments, closing fees, mortgage interest rate buydowns, and initial property escrow pre-paids.
However, as of August 2026, it is vital for prospective buyers to understand that this federal bill has not been passed into law. It remains pending in Congress. You cannot currently fill out a federal application or receive a payout directly from the U.S. government under this specific act.
While the national headline-grabbing grant is still waiting on Congressional approval, that does not mean down payment assistance is off the table. Many active state housing finance agencies and municipal programs offer up to $25,000—or even more—in forgivable grants, deferred loans, and zero-percent assistance for buyers who qualify. You can read a complete breakdown of current national legislation and proposal timelines in What Is the $25,000 Down Payment Toward Equity Act? | 2026 .
Status of the Downpayment Toward Equity Act
The Downpayment Toward Equity Act was introduced as a major federal effort allocating an estimated $175 billion in grant subsidies. Administered through the U.S. Department of Housing and Urban Development (HUD), state housing finance authorities, and participating community nonprofits, the proposal targets buyers who historically lacked access to intergenerational equity.
Under the current 2025/2026 legislative draft, the standard baseline grant would equal the greater of $20,000 or 10% of the home’s purchase price. For buyers categorized as socially or economically disadvantaged, the grant cap increases up to $25,000.
Because legislative calendars in Washington remain unpredictable, smart buyers shouldn’t press pause on their homeownership dreams waiting for federal action. Exploring currently funded state and regional initiatives provides a much faster, guaranteed path to getting key assistance. For a deeper look at active grant frameworks across the country, check out the $25,000 First-Time Home Buyer Grants In US: Full Guide 2026 .
Repayment Rules and Forgiveness Terms
One of the most appealing aspects of true homebuyer grants—and proposed federal legislation—is the potential for complete loan forgiveness. Unlike standard second mortgages that add to your monthly overhead, forgivable down payment assistance structured as a grant typically requires zero monthly payments.
Under the proposed Downpayment Toward Equity Act and similar state-level forgivable grant structures, forgiveness operates on a time-based scale:
- 0 to 12 Months: 100% repayment required if the home is sold or no longer serves as your primary residence.
- Year 2: 80% repayment required.
- Year 3: 60% repayment required.
- Year 4: 40% repayment required.
- Year 5: 20% repayment required.
- After 5 Years: 0% repayment required — 100% of the grant principal is permanently forgiven.
If a buyer sells the home prior to completing the required 5-year residency period, repayment is generally capped at the net proceeds or profit realized from the sale.
Eligible grant expenses generally include:
- Upfront principal down payment reduction
- Lender fees, title insurance, and closing costs
- Discount points used to permanently buy down your mortgage interest rate
- Accessibility modifications and necessary upfront repairs required for loan approval
Active State Programs Offering a $25,000 Grant to Buy a House

Even without federal passage of the Downpayment Toward Equity Act, homebuyers across the country—and especially here in California—have access to powerful, state-specific financial tools designed to cover down payments and closing fees.
| Region / Agency | Program Name | Max Assistance | Structure / Terms | Key Eligibility |
|---|---|---|---|---|
| California (CalHFA) | Dream For All / MyHome | Up to 20% or $25k+ | Shared Appreciation / Deferred 2nd | First-time buyers, AMI caps |
| Massachusetts | MassHousing DPA | Up to $25,000 – $30,000 | 0% Deferred or Low-rate 15-yr | Income up to 135% AMI |
| Michigan | MSHDA First-Gen DPA | $25,000 | Deferred 0% Loan | First-generation buyers, 640 min credit |
| Connecticut | CHFA Time To Own | Up to $25,000 | 0% Interest, 10-Yr Forgivable | 10% forgiven annually over 10 yrs |
| Detroit, MI | Detroit DPA | Up to $25,000 | Direct Municipal Grant | 12-month resident, 80% AMI cap |
California Down Payment Assistance Options
In California’s competitive real estate landscape, buyers need specialized options to navigate higher median purchase prices. At Capital Home Mortgage California, we actively guide local buyers through top state and municipal assistance structures.
- CalHFA Dream For All Shared Appreciation Loan: Offers qualifying first-time and first-generation buyers up to 20% of the purchase price (often well exceeding $25,000) to apply toward down payment or closing costs. You repay the original principal plus a specified percentage of the home’s value appreciation when you sell or refinance. Learn more at the official California Dream For All | Shared Appreciation Loan – CalHFA – CA.gov portal.
- CalHFA MyHome Assistance Program: Provides a deferred-payment second mortgage to cover down payment and closing costs up to 3.5% for FHA loans or 3% for conventional loans. Payments are deferred until the home is sold, refinanced, or paid off.
- Local Municipal Grants: Many individual cities and counties throughout California maintain dedicated housing trust funds. For instance, check out local programs like the Santa Ana Down Payment Assistance Programs which offer targeted funds for regional residents.
Additional State and Municipal Grants Across the US
Outside California, state housing authorities have created innovative programs targeting local affordability needs:
- Massachusetts (MassHousing): Offers eligible first-time buyers up to $25,000 in zero-percent deferred assistance or low-rate 15-year amortizing second loans, with income limits reaching up to 135% of Area Median Income.
- Michigan (MSHDA): Launched a $25,000 First-Generation Down Payment Assistance deferred loan funded by state budget appropriations for buyers whose parents have not owned a home in the past three years.
- Connecticut (CHFA): Provides the “Time To Own” forgivable loan up to $25,000 at 0% interest and $0 monthly payment, forgiving 10% of the principal balance each year over a 10-year period.
- Regional Lender Grants: Member banks partnered with Federal Home Loan Banks (FHLB) frequently issue regional grants, such as the $20K Grant from FHLB Dallas and BankPlus Paves the Way for Mississippi Family’s First Home Purchase | AP News initiative.
Eligibility Guidelines and Household Income Limits

Qualifying for a $25,000 grant to buy a house requires meeting strict household income limits, homeownership history rules, and credit benchmarks set by the funding agency.
How to Qualify for a $25,000 Grant to Buy a House
While specific program rules vary by location and government agency, standard eligibility framework rules include:
- First-Time Homebuyer Status: Defined as an individual or family who has not held an ownership interest in a primary residence during the preceding 3-year (36-month) period.
- First-Generation Homebuyer Status: Many advanced $25,000 grant programs require that the buyer’s parents or legal guardians do not currently own a home (or did not own one at the time of their passing). Former foster care youth automatically satisfy first-generation eligibility criteria under most program guidelines.
- Area Median Income (AMI) Thresholds: Income caps generally restrict eligibility to buyers earning at or below 80% to 120% of their county’s Area Median Income. In high-cost real estate markets (like Los Angeles, San Francisco, Orange County, San Diego, and San Jose), these limits are frequently adjusted upward to 140% or 180% AMI to accommodate local living costs.
- Credit Score Requirements: Most government-backed DPA programs paired with FHA or conventional first loans require a minimum credit score ranging between 620 and 640.
- Owner-Occupancy Rule: You must occupy the property as your primary residence. Investment properties, second homes, and vacation rentals are strictly prohibited.
Applying for a $25,000 Grant to Buy a House Step-by-Step
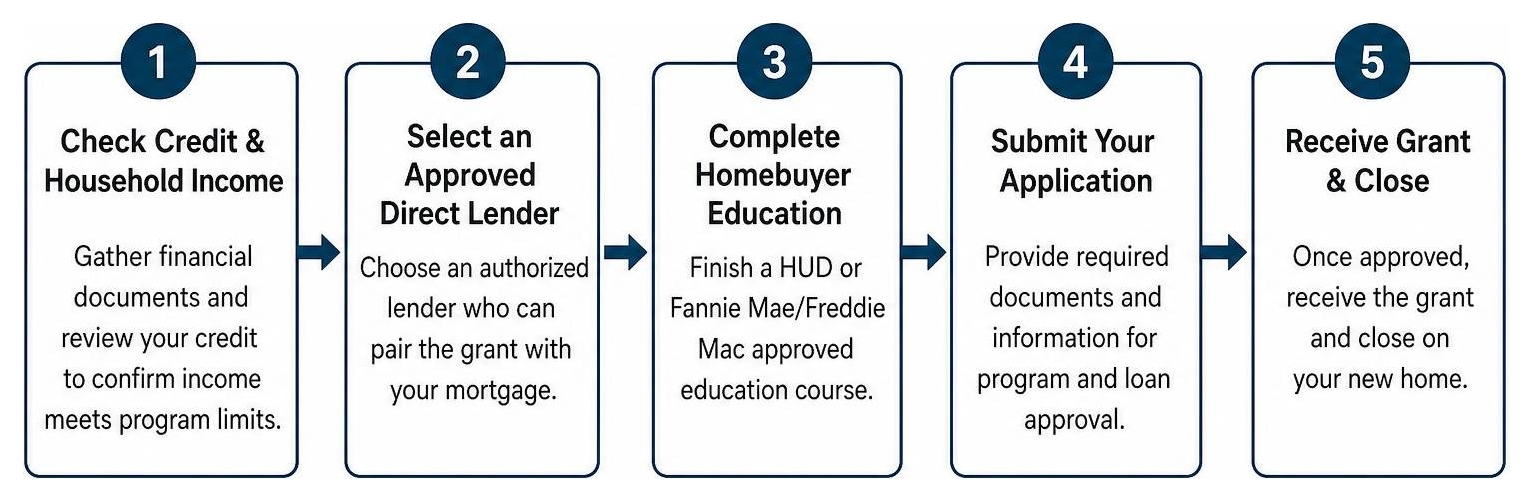
Securing down payment assistance is simple when you follow a structured, step-by-step roadmap:
- Check Credit and Household Income: Gather recent tax returns, W-2s, pay stubs, and check your credit report to verify that your household income falls within local Area Median Income caps.
- Select an Approved Direct Lender: Work with an experienced, direct mortgage lender like Capital Home Mortgage California that is authorized to approve and pair down payment assistance programs directly with primary mortgage loans.
- Complete Homebuyer Education: Most grant programs require applicants to complete a short homebuyer education course certified by HUD or Fannie Mae/Freddie Mac.
- Get Mortgage Pre-Approval: Obtain a formal mortgage pre-approval that combines your primary home loan with your selected down payment assistance program.
- Shop for an Eligible Home and Close: Work with your real estate agent to find a home within local program price limits, submit your contract, and let your lender process your grant funds directly to the closing table.
Qualifying Property Types and Compatible Mortgage Loans
Down payment assistance grants are designed to support stable residential neighborhoods. As a result, qualifying properties must meet standard safety and structural guidelines.
Eligible property types generally include:
- Single-family detached residential homes
- Approved condominiums and townhomes
- Multi-unit residential properties (up to 4 units), provided the borrower occupies one unit as their primary residence
- Manufactured homes on permanent foundations (explore the distinct structural and financing benefits via California Manufactured Homes Advantages)
Understanding prevailing property values is critical when applying for assistance in fast-moving regions. To stay informed on current market dynamics, see What’s Happening with California Real Estate Prices in 2025?.
Compatible First Mortgage Loan Types
A down payment grant or deferred second loan cannot exist in a vacuum—it must be paired with an approved first mortgage loan. Most state and municipal programs allow pairing with standard home loans, including:
- FHA Loans: Ideal for buyers with lower credit scores or smaller savings. Requires just 3.5% down, which can be fully covered by grant funds.
- VA Loans: Zero-down-payment mortgages for eligible military veterans and active-duty service members. Grants can be applied toward closing costs and interest rate buydowns.
- USDA Loans: Zero-down-payment financing for homes located in designated rural and suburban areas.
- Conventional Mortgages: Standard 3% down payment programs (such as HomeReady or Home Possible) ideal for buyers with solid credit profiles.
Frequently Asked Questions About Homebuyer Assistance
Is the $25,000 grant currently available nationwide?
No. The federal Downpayment Toward Equity Act, which proposes up to $25,000 for first-generation buyers nationwide, has not passed Congress. However, individual state and local housing agencies offer active programs supplying up to $25,000 or more in local assistance.
Do I have to repay the $25,000 home grant?
True grants do not require repayment. Forgivable loans require zero repayment as long as you occupy the home as your primary residence for a set period (typically 5 to 10 years). Deferred second mortgage programs do not require monthly payments, but the principal is repaid when you sell, refinance, or pay off your primary mortgage.
What are the income limits to qualify for down payment grants?
Income limits are based on local Area Median Income (AMI) and household size. Most programs limit eligibility to buyers earning between 80% and 120% AMI, though high-cost regions in California frequently expand income thresholds up to 140% or 180% AMI.
Conclusion
Finding a $25,000 grant to buy a house requires separating federal bill headlines from active, operational programs. While Congress continues to deliberate on national grant legislation, active state, county, and municipal programs in California are helping buyers step into homeownership today.
At Capital Home Mortgage California, we pride ourselves on delivering end-to-end mortgage guidance, in-house loan processing, competitive interest rates, and seven-day-a-week support. Whether you’re exploring FHA loans, conventional financing, or specialized programs like Santa Ana Down Payment Assistance Programs, our direct lending team is ready to structure the perfect mortgage for your needs.
Contact Capital Home Mortgage California today to evaluate your eligibility for down payment assistance and secure pre-approval for your new home!


