
Understanding the HECM Mortgage: What It Is and How It Works
#
A HECM mortgage — short for Home Equity Conversion Mortgage — is the only reverse mortgage insured by the U.S. federal government, and it lets homeowners 62 or older convert their home equity into tax-free cash without making monthly mortgage payments.
Here’s what you need to know at a glance:
- What it is: A federally backed (FHA-insured) reverse mortgage for seniors
- Who qualifies: Homeowners age 62+, living in their primary residence
- How much you can access: Up to the 2026 FHA lending limit of $1,249,125
- How you get paid: Lump sum, monthly payments, line of credit, or a combination
- When you repay: Only when you sell, move out, or pass away
- Key obligation: You must keep up with property taxes, insurance, and home maintenance
For many California homeowners, retirement looks like this: a home worth hundreds of thousands of dollars, but a tight monthly cash flow. A HECM can bridge that gap — but it comes with real costs, rules, and trade-offs worth understanding before you decide.
I’m Dale Gremillion, a Senior Loan Officer and Producing Branch Manager at Capital Home Mortgage California, with over 25 years of experience in residential mortgage lending — including extensive work with HECM mortgage products across a wide range of retirement scenarios. In this guide, I’ll walk you through everything you need to evaluate whether a HECM is the right fit for your retirement plan.
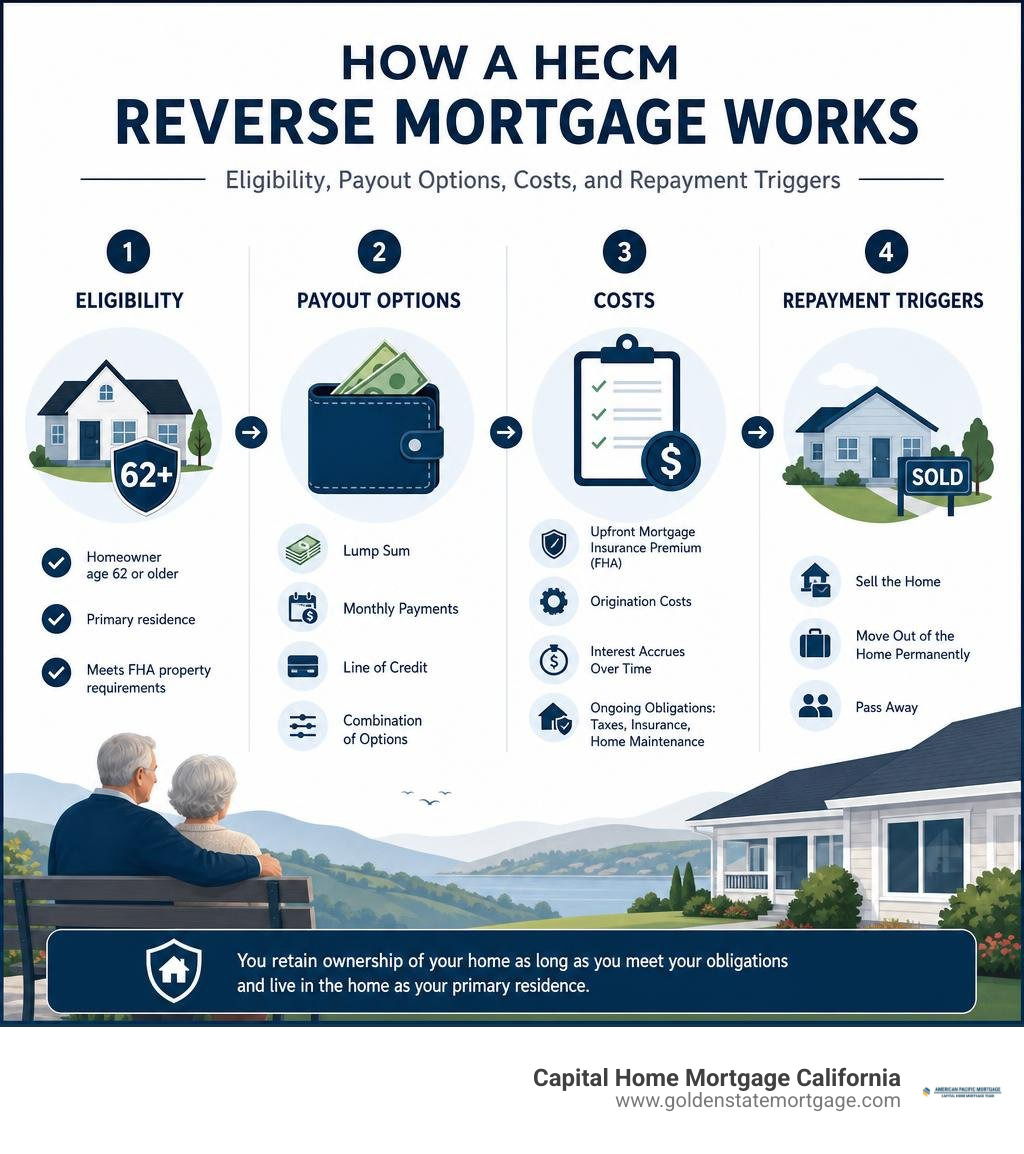

A Home Equity Conversion Mortgage (HECM) is a specialized type of reverse mortgage designed under Section 255 of the National Housing Act and backed by the Federal Housing Administration (FHA). Unlike traditional “forward” mortgages where you make monthly payments to a lender to build equity, a HECM mortgage works in reverse: the lender pays you, tapping into the home equity you have accumulated over decades.
The defining feature of a HECM is that you remain the sole owner on the property title. You are not signing over your home to the bank. As long as you fulfill basic loan obligations, you do not have to make any monthly principal or interest payments. Instead, loan interest and fees compound monthly and are added to the outstanding balance, which is repaid when the last surviving borrower permanently leaves the property.
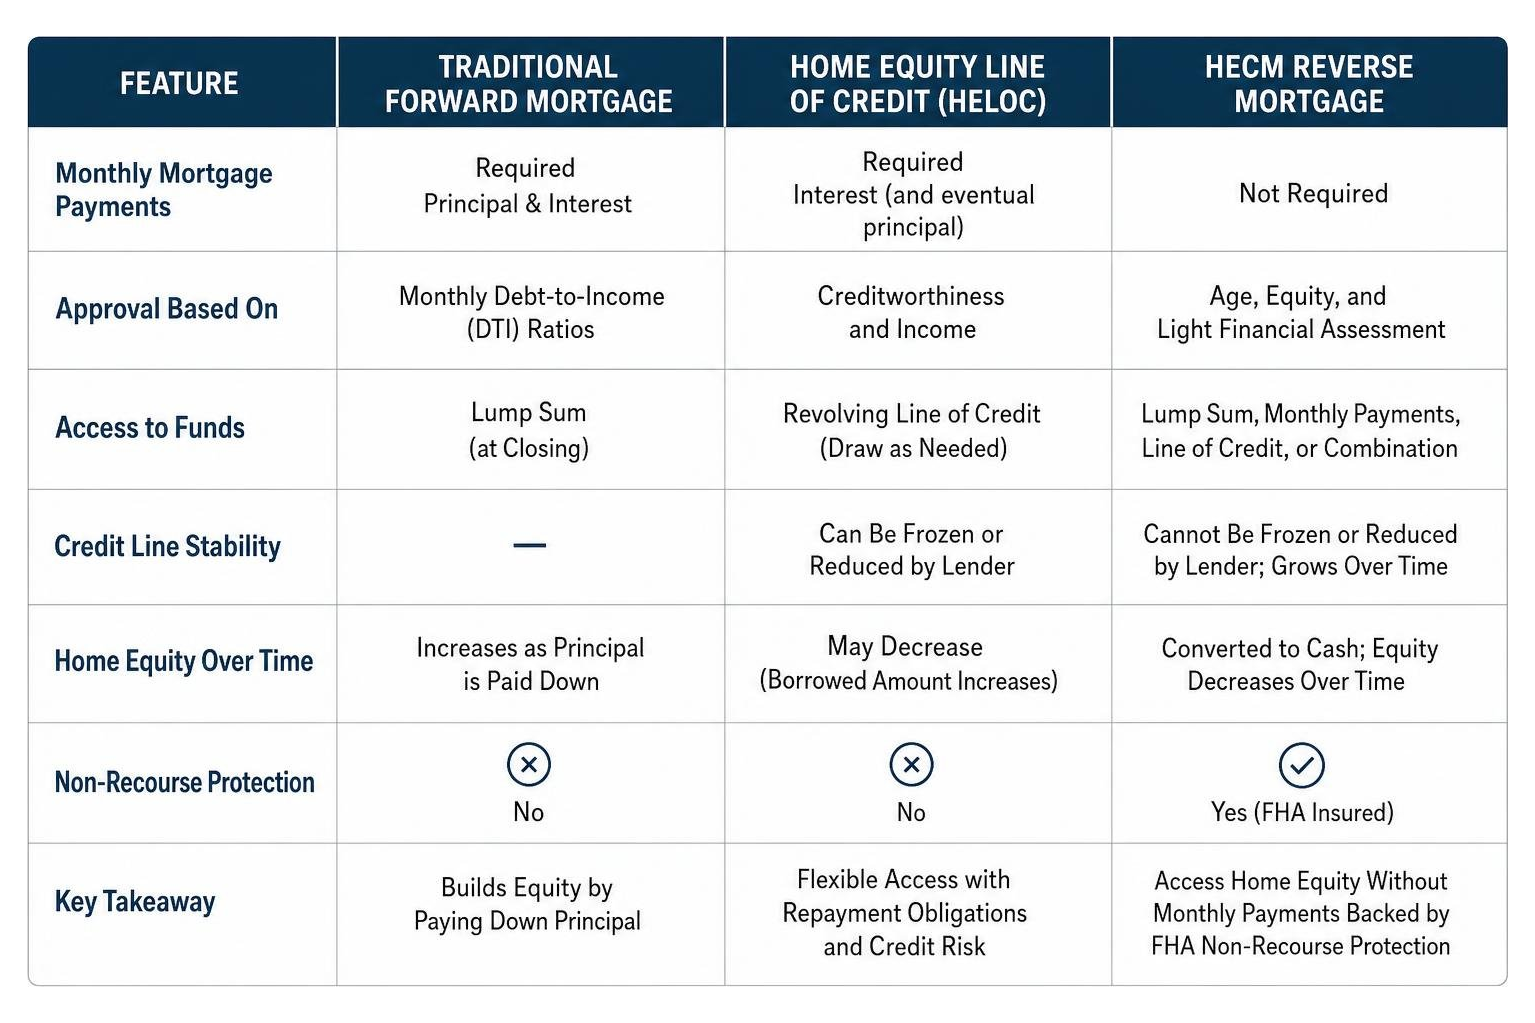
To better understand how a reverse mortgage compares to traditional home loans, consider these key differences:
- Traditional Forward Mortgage: Requires monthly principal and interest payments. Approval depends heavily on monthly debt-to-income (DTI) ratios. Paying down the principal increases home equity over time.
- Home Equity Line of Credit (HELOC): Provides a revolving credit line but requires immediate interest payments (and eventual principal repayment). The lender can freeze or reduce your credit limit at any time during market downturns.
- HECM Reverse Mortgage: Requires no monthly mortgage payments. Approval is based on borrower age, equity, and a light financial assessment. Crucially, an unused HECM line of credit cannot be frozen or reduced by the lender and actually grows over time.
Because a HECM mortgage is insured by the FHA, it offers non-recourse protection. This means neither you nor your heirs will ever owe more than the fair market value of the home when the loan comes due, even if the total loan balance grows larger than the home’s market value. To explore official program guidelines, you can review the HUD FHA Reverse Mortgage Guidelines.
Eligibility, Principal Limits, and Payment Options
The total pool of funds you can access through a HECM mortgage is known as the Principal Limit. Rather than letting you borrow 100% of your home value, HUD uses mathematical Principal Limit Factors (PLFs) to calculate your available loan amount based on three primary variables:
- Age of the Youngest Borrower: (or Eligible Non-Borrowing Spouse). Older borrowers qualify for a higher percentage of their home equity.
- Current Interest Rates: Lower interest rates increase your principal limit, while higher rates lower the available proceeds.
- Maximum Claim Amount (MCA): The lesser of your home’s appraised fair market value, the purchase price, or the prevailing FHA national reverse mortgage lending limit.
For 2026, the FHA national maximum claim limit is $1,249,125, up from $1,209,750 in 2025 (and $1,149,825 in 2024). If your California home is appraised at $1,000,000, your maximum claim amount is $1,000,000. If your home is valued at $1,500,000, your loan limit for calculation purposes is capped at the 2026 limit of $1,249,125.
Qualifying for a HECM Mortgage as a Senior
To qualify for a HECM loan through Capital Home Mortgage California, you must satisfy federal eligibility requirements:
- Age Requirement: The youngest borrower (or non-borrowing spouse) must be at least 62 years old at the time of application.
- Primary Residence: The property must be your principal residence, where you live for more than six months out of the year.
- Property Types: Eligible homes include single-family homes, 2-to-4-unit owner-occupied properties, HUD-approved condominiums, and manufactured homes meeting FHA standards.
- Existing Liens: You must either own your home outright or have substantial equity. Any existing mortgage or lien must be paid off entirely at closing using your HECM proceeds or cash on hand.
- Financial Assessment: Lenders conduct a basic financial evaluation reviewing income, credit history, and property tax/insurance payment records to verify your ability to maintain ongoing housing costs.
- Mandatory HUD Counseling: Before applying, you must complete an independent counseling session with a HUD-approved housing counselor (either in person or over the phone).
Payout Structures: Fixed vs. Adjustable Rate Options
How you receive your funds depends on whether you select a fixed-rate or an adjustable-rate HECM mortgage. HUD regulations limit fixed-rate loans to a single, lump-sum disbursement at closing. Conversely, adjustable-rate HECMs offer flexible payment plans linked to the CME Term SOFR index (which officially replaced the retired LIBOR index for reverse mortgages).
Under federal guidelines, borrowers are subject to the 60% first-year utilization rule. In the first 12 months after closing, you cannot withdraw more than 60% of your approved principal limit, unless additional funds are required to pay off mandatory obligations (such as an existing forward mortgage balance or mandatory closing costs) plus up to an additional 10%.
The table below outlines how each payout structure operates:
| Payout Structure | Interest Rate Type | How Funds Are Distributed | Key Benefit |
|---|---|---|---|
| Single Lump Sum | Fixed Rate | Full allowable advance disbursed at closing | Provides immediate upfront cash to pay off large existing liens or debts |
| Line of Credit | Adjustable Rate | Draw funds on demand up to your credit limit | Unused credit limit grows over time at the same compounding rate as the loan interest |
| Tenure Payout | Adjustable Rate | Fixed monthly payments for as long as you live in the home | Functions like a guaranteed monthly annuity check without selling the property |
| Term Payout | Adjustable Rate | Fixed monthly payments for a fixed number of years (e.g., 10 years) | Maximizes cash flow during a specific retirement window |
| Modified Combination | Adjustable Rate | Combines a line of credit with monthly tenure or term payments | Offers predictable monthly income alongside an emergency reserve fund |
A major benefit of an adjustable-rate HECM line of credit is its growth feature. If you leave a portion of your credit line untouched, the available balance grows at the loan’s interest rate plus the annual mortgage insurance premium rate. This means your available borrowing capacity increases automatically over time regardless of property value changes.
Costs, Obligations, and Non-Borrowing Spouse Protections

While a HECM mortgage provides financial flexibility during retirement, it is important to evaluate the associated fees and ongoing responsibilities. Most upfront closing costs can be financed directly into the loan balance, meaning you do not need out-of-pocket cash at closing, though doing so reduces your net available principal limit.
Upfront Fees and Ongoing Costs of a HECM Mortgage
The cost structure of an FHA-insured HECM reverse mortgage includes both upfront and ongoing fees:
- Origination Fee: Capped by law at a maximum of $6,000. Lenders calculate this as 2% of the first $200,000 of maximum claim amount, plus 1% of any amount over $200,000. Up to $1,800 of this fee can be financed into the loan balance under federal rules.
- Upfront Mortgage Insurance Premium (Initial MIP): FHA charges an initial MIP equal to 2.0% of the maximum claim amount at closing.
- Annual Mortgage Insurance Premium: An ongoing annual MIP of 0.50% of the outstanding loan balance is charged and added to the loan balance monthly. This fee funds the FHA insurance pool that guarantees non-recourse protections.
- Third-Party Closing Costs: Appraisal fees, title search and insurance, recording fees, and mandatory HUD counseling fees ($125–$200 on average).
- Servicing Fees: Lenders may charge a monthly servicing fee (typically $25 to $35), which is added to the loan balance.
For a comprehensive detailed breakdown of reverse mortgage financing costs, you can consult the Investopedia HECM Cost Overview.
Borrower Obligations and Deferral Periods for Spouses
Taking out a HECM mortgage eliminates monthly mortgage payments, but you retain full responsibility for property charges. To keep the loan in good standing, you must:
- Maintain the home as your primary residence.
- Pay all property taxes and special municipal assessments on time.
- Maintain hazard and flood insurance coverage.
- Keep the physical property in reasonable repair.
If a borrower fails to meet financial assessment guidelines regarding property charges, the lender may establish a Fully Funded Life Expectancy Set-Aside (LESA). A LESA deducts a calculated portion of your principal limit at closing to pay property taxes and insurance on your behalf throughout your statistical life expectancy.
Special federal protections exist for non-borrowing spouses. If a married homeowner takes out a HECM without including their younger spouse on the loan (for instance, if the spouse was under 62 at closing), the non-borrowing spouse is classified as an Eligible Non-Borrowing Spouse. Under FHA rules, if the borrowing spouse passes away, the loan enters a Deferral Period. This defers the loan’s due-and-payable status, allowing the surviving non-borrowing spouse to remain living in the home indefinitely, provided they maintain the property and meet all tax and insurance obligations. To review legal contractual language governing these protections, refer to the HUD Model Loan Agreement.
Loan Repayment, Key Risks, and Smart Alternatives
A HECM mortgage does not require monthly payments, but it must eventually be repaid. Understanding when repayment is triggered and evaluating potential alternatives will help you make an informed decision for your estate.
When the Loan Comes Due and Options for Heirs
A reverse mortgage becomes due and payable when one of the following maturity events occurs:
- The last surviving borrower (or Eligible Non-Borrowing Spouse) passes away.
- The home is sold or title to the property is transferred.
- The property stops being the primary residence of the borrower (e.g., the borrower permanently moves out).
- The borrower is absent from the home for more than 12 consecutive months due to physical or mental illness (such as an extended stay in a nursing home or healthcare facility).
- The borrower defaults on property taxes, homeowner’s insurance, or property maintenance obligations.
When the loan becomes due, your heirs have clear options under FHA regulations:
- Sell the Property: Heirs can sell the home, pay off the HECM balance, and keep 100% of the remaining equity.
- Pay 95% of Appraised Value: If the outstanding loan balance exceeds the home’s market value, heirs can satisfy the loan in full by paying 95% of the current appraised fair market value (or selling the home for 95% of market value). FHA insurance absorbs any remaining loan loss.
- Refinance into a Forward Mortgage: Heirs can refinance the loan into a standard forward mortgage or pay off the loan balance using external personal funds to keep the home in the family.
Heirs typically receive six months from the borrower’s passing to resolve the loan, with potential extensions granted by HUD if active repayment efforts are demonstrated.
Alternatives: Downsizing, HELOCs, and Jumbo Reverse Mortgages
Before committing to a reverse mortgage, we recommend exploring all financial alternatives with our team at Capital Home Mortgage California:
- Downsizing: Selling your current residence to purchase a smaller, less expensive home frees up equity without incurring mortgage insurance premiums or compounding interest fees.
- HELOC or Home Equity Loan: If you have sufficient monthly income to qualify and comfortably manage monthly payments, a standard HELOC or cash-out refinance may offer lower upfront closing costs.
- Proprietary (Jumbo) Reverse Mortgages: For high-value home properties in California valued well above the 2026 FHA limit of $1,249,125, proprietary jumbo reverse mortgages allow access to higher loan amounts up to $4 million or $6 million without FHA mortgage insurance premiums.
Frequently Asked Questions About HECM Loans
Can I use a HECM to buy a new primary residence?
Yes. Under the HECM for Purchase program, seniors 62 and older can buy a new primary residence in a single transaction. You combine loan proceeds from the HECM with cash on hand (from the sale of a prior home or savings) to cover the purchase price gap. This eliminates monthly mortgage payments on your new residence while preserving more of your retirement cash reserves.
Will HECM proceeds affect my Social Security or Medicare benefits?
Generally, no. Proceeds from a HECM mortgage are considered loan advances, not earned income. Therefore, they are non-taxable and do not impact standard Medicare or Social Security retirement benefits. However, because large cash lump sums retained in a bank account could potentially affect need-based public assistance programs like Medicaid or Supplemental Security Income (SSI), proceeds should be spent in the month received.
What happens if my loan balance exceeds my home’s value?
Because a HECM mortgage is a non-recourse loan insured by the FHA, you and your estate are fully protected. If real estate market values decline and your accumulated loan balance ends up higher than the home’s appraised sale value, neither you nor your heirs are personally liable for the deficit. The FHA insurance fund absorbs the difference.
Conclusion
A HECM mortgage can serve as an effective tool in a complete retirement financial plan, helping senior homeowners unlock equity, eliminate monthly mortgage payments, establish growing emergency reserves, or purchase a retirement residence. By understanding its costs, obligations, and spousal protections, you can determine if a reverse mortgage matches your long-term estate goals.
At Capital Home Mortgage California, we specialize in providing personalized, transparent mortgage guidance across California—from Los Angeles and San Diego to San Jose, San Francisco, Sacramento, Riverside, Fresno, and Irvine. With in-house processing for fast, on-time closings and seven-day-a-week support, our experienced loan specialists are ready to help you evaluate your options.
Ready to explore how home equity can strengthen your retirement cash flow? Contact us today to Explore California Reverse Mortgage Options and receive a personalized HECM evaluation from our expert team.


