
When You Need a Reverse Mortgage Attorney in California: What’s at Stake
If you’re looking for a reverse mortgage attorney in California, here’s what you need to know right away:
Who needs a California reverse mortgage attorney?
- Heirs who discover a parent died with a reverse mortgage and face foreclosure
- Seniors who believe they were misled, pressured, or defrauded into a reverse mortgage
- Families suspecting a caregiver or sibling diverted reverse mortgage funds
- Executors or administrators managing a California probate involving a reverse-mortgaged home
- Surviving spouses not listed on the original reverse mortgage loan
What a reverse mortgage attorney can do for you:
- Stop or delay foreclosure after a borrower’s death using California probate law
- File elder financial abuse claims under California’s Elder Abuse Act
- Recover double damages and attorney fees if fraud or undue influence is proven
- Seek contract rescission if a senior lacked mental capacity at signing
- Navigate probate court and secure IAEA authority to sell the home quickly
Reverse mortgages promise financial relief for older homeowners. For many seniors, tapping into home equity without making monthly payments sounds like a smart solution. But the reality is often far more complicated — and sometimes far more damaging.
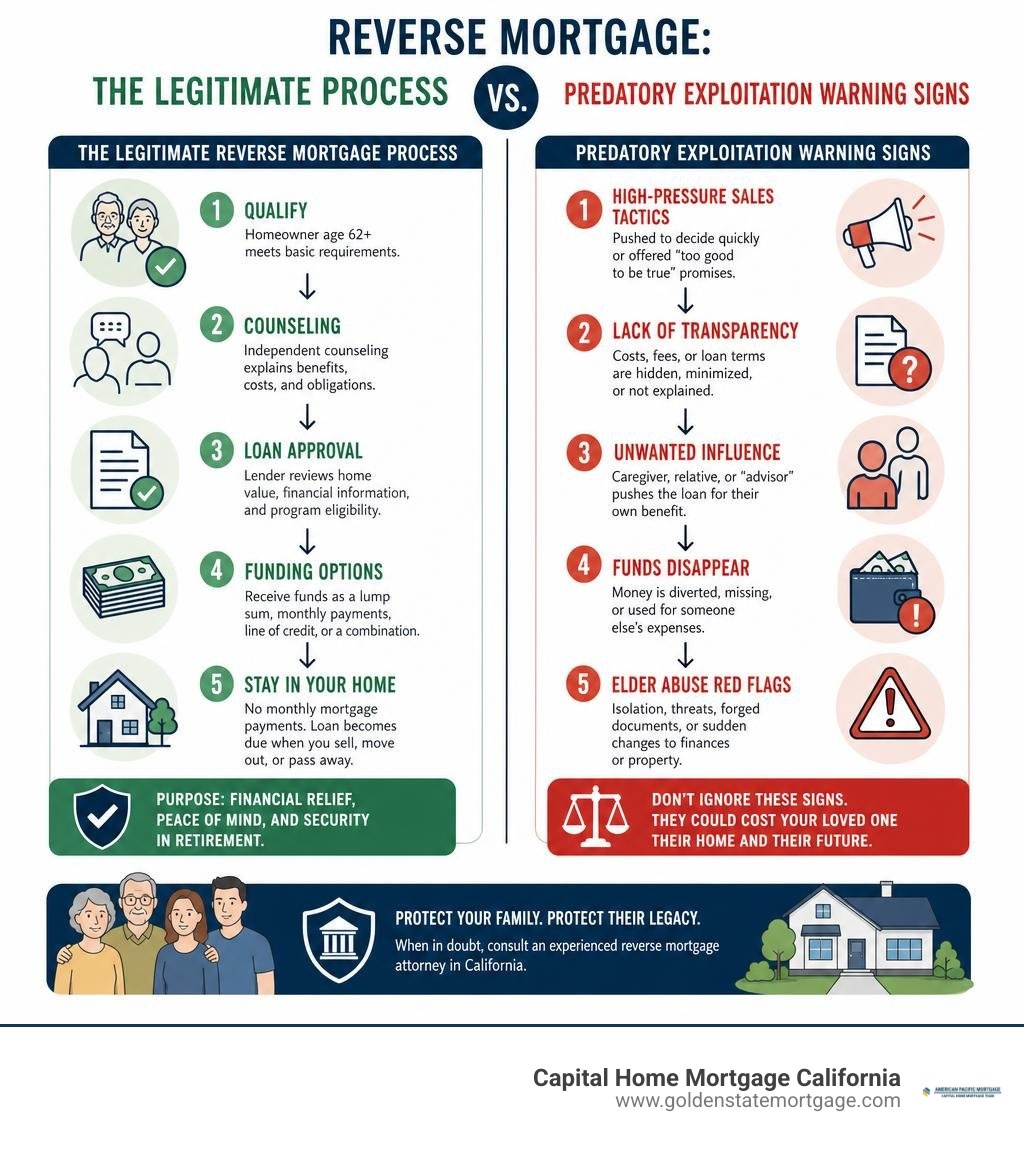
Homeowners must be 62 or older to qualify. The loan doesn’t come due until they sell, move out, or pass away. That sounds simple. But when a borrower dies, heirs can find themselves scrambling against aggressive loan servicers, tight legal deadlines, and — in the worst cases — discovering that a trusted person exploited their loved one to drain the home’s equity entirely.
The Consumer Financial Protection Bureau fined three reverse mortgage companies nearly $800,000 in 2016 alone for deceptive advertising. And California’s Elder Abuse Act exists precisely because financial exploitation of seniors is that common.
This guide explains how reverse mortgages work, how abuse happens, and exactly when to call an attorney before it’s too late.
I’m Dale Gremillion, Senior Loan Officer and Producing Branch Manager at Capital Home Mortgage California, with over 25 years of residential mortgage lending experience — including reverse mortgage products — giving me insight into where legitimate lending ends and where you may need a reverse mortgage attorney in California to protect your family. That context shapes everything I’ll walk you through below.
How Reverse Mortgages Work in California and Common Risks
At its core, a Home Equity Conversion Mortgage (HECM) — the standard federally insured reverse mortgage — allows homeowners aged 62 or older to convert a portion of their accumulated home equity into tax-free cash payments, a line of credit, or a lump sum. Unlike a traditional forward mortgage where you make monthly payments to reduce principal, a reverse mortgage accrues interest month after month while principal repayment is deferred until a maturity event occurs.
To maintain a reverse mortgage in good standing in California, the borrower must fulfill strict ongoing requirements:
- Maintain the property as their primary residence.
- Pay all property taxes and homeowners insurance on time.
- Keep the home in good physical condition and pay any local assessment fees or HOA dues.
While mandatory Housing and Urban Development (HUD) counseling is required before any California senior can sign an HECM agreement, the reality is that compounding interest slowly erodes home equity over time. This structure creates significant exposure when property values shift or when unexpected life events arise, such as taking a long-term look at What’s Happening with California Real Estate Prices in 2025?.
The risks multiply dramatically under specific conditions:
- Non-Borrowing Spouses: If only one spouse was listed on the loan documents (often because the younger spouse was not yet 62 at signing), the non-borrowing spouse can face immediate repayment demands or eviction when the borrowing spouse passes away or moves into extended care.
- Tax and Insurance Default: Failure to pay property taxes or homeowner insurance prompts the loan servicer to declare a technical default, accelerating loan balance collection and initiating foreclosure.
- Rapid Equity Depletion: High origination fees, closing costs, and monthly compounding interest rates quickly absorb equity that seniors originally planned to pass along to their heirs.
Recognizing Reverse Mortgage Abuse and Financial Elder Abuse
Because reverse mortgages unlock substantial pools of unencumbered home equity, predatory actors frequently target vulnerable senior citizens. Understanding how these schemes work is critical to protecting your family’s financial security.
Predatory lending schemes often merge reverse mortgages with third-party products or services:
- Annuity Bundling: Unscrupulous financial advisers pressure seniors to pull equity out through a 4.5% interest reverse mortgage to purchase a deferred annuity paying only 3% return. This guarantees a ongoing net financial loss for the senior while netting the promoter lucrative commissions.
- Vendor and Contractor Fraud: Unprincipled home repair companies convince seniors to execute an HECM to finance overpriced, shoddy, or entirely unperformed home remodeling projects.
- Property Flipping and HECM for Purchase Scams: Fraudulent real estate operators sell dilapidated or overvalued properties to seniors using HECM for Purchase loans, pocketing high kickbacks while leaving the senior with structural nightmares.
- Deceptive Advertising: Loan companies market reverse mortgages as “free money from the government” or falsely claim borrowers can never lose their home under any circumstances. In 2016, the CFPB penalised three major reverse mortgage providers nearly $800,000 for these misleading marketing tactics.
When a senior contracts for a loan while lacking legal mental capacity due to dementia or cognitive decline, California common law and statutory rules make those agreements voidable. For deeper background on civil claims arising from predatory reverse mortgage practices, read about Fraud with Reverse Mortgages.
Red Flags That Require Consulting a Reverse Mortgage Attorney California Seniors Can Count On
Financial elder abuse frequently happens behind closed doors, orchestrated by caregivers, neighbors, or even family members. Recognizing early warning indicators allows families to intervene before all equity disappears.
Watch out for these critical red flags:
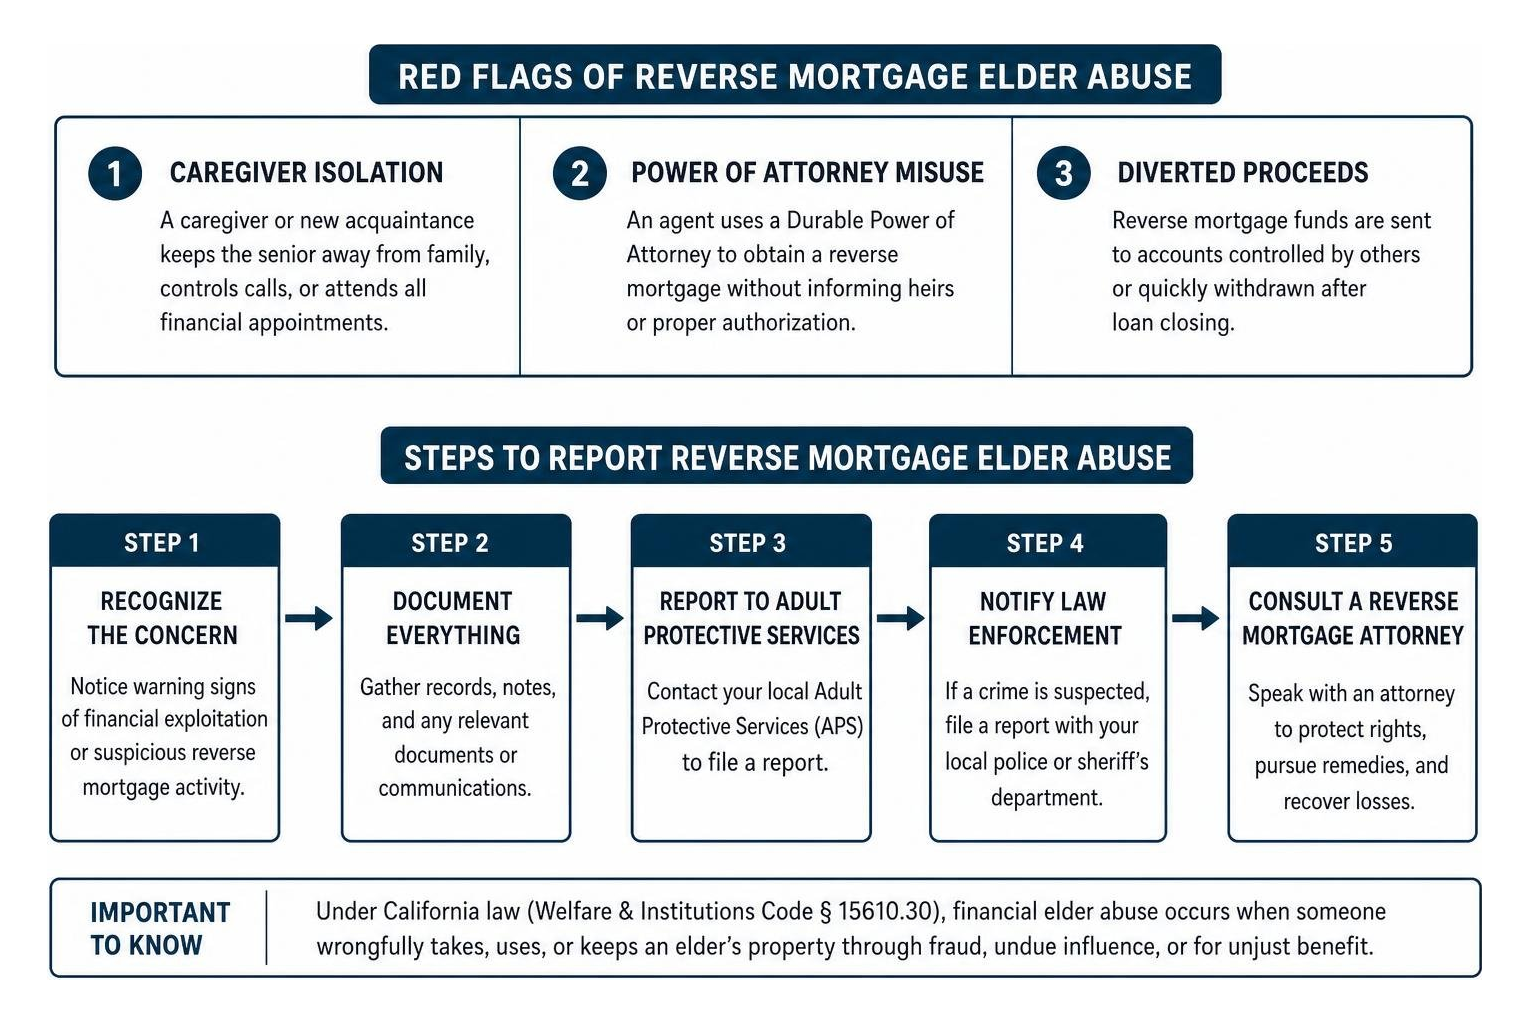
- Caregiver Isolation: A live-in aide or new acquaintance actively keeps the senior away from family, controls incoming phone calls, or attends all financial appointments.
- Power of Attorney Misuse: An agent under a Durable Power of Attorney executes a reverse mortgage without telling legal heirs or without authorization under the trust agreement.
- Diverted Proceeds: Reverse mortgage cash distributions are routed to joint accounts controlled by third parties or immediately wired out after loan closing.
Under California Welfare and Institutions Code section 15610.30, financial elder abuse occurs whenever a person or entity takes, secretes, appropriates, obtains, or retains real or personal property of an elder for wrongful use or with intent to defraud, or through undue influence. A qualified reverse mortgage attorney california seniors rely on uses this statute to hold bad actors accountable.
When to Hire a Reverse Mortgage Attorney California Families Trust
Hiring an attorney becomes urgent whenever informal attempts to resolve servicer disputes fail or when financial fraud is discovered. A dedicated reverse mortgage attorney california families trust provides civil remedies that go beyond standard mortgage counseling.
California’s Elder Abuse and Dependent Adult Civil Protection Act offers potent statutory remedies:
- Mandatory Attorney Fees: Courts can order defendants who commit elder abuse to reimburse all reasonable legal fees incurred by the victim or estate.
- Double or Treble Damages: Statutory provisions allow judges or juries to award double or triple damages when financial elder abuse involves bad faith, fraud, or intentional malice.
- Contract Rescission: Courts can invalidate and cancel reverse mortgage contracts procured through undue influence or executed while a senior lacked capacity.
- Constructive Trusts: Judges can place legal encumbrances on diverted assets or bank accounts, preventing bad actors from spending stolen loan proceeds during active litigation.
How a Reverse Mortgage Attorney California Experts Recommend Stops Foreclosure
When a borrower passes away or defaults on taxes, reverse mortgage loan servicers immediately issue acceleration notices. If left unchecked, the servicer rapidly refers the file to a foreclosure trustee to issue a Notice of Default followed by a Notice of Trustee’s Sale.
A seasoned reverse mortgage attorney california experts recommend employs specific legal strategies to stop pending foreclosures:
- Formal Servicer Extensions: Servicers are federally required under HUD rules to grant up to two 60-day extensions when heirs demonstrate active, good-faith efforts to sell or refinance the property.
- Temporary Restraining Orders (TROs): If a loan servicer refuses to grant reasonable extensions or schedules a sale during probate, an attorney can file an emergency ex parte application for a TRO in California Superior Court to halt the trustee sale.
- California Homeowner Bill of Rights (HBOR) Enforcement: Servicers who engage in dual tracking—proceeding with foreclosure while evaluating probate extension documentation—violate California HBOR rules, opening the door to injunctions and statutory damages.
Navigating Heirs’ Rights, Probate, and Foreclosure After a Borrower’s Death
When a reverse mortgage borrower passes away, the loan balance becomes due and payable. However, heirs are not personally liable for any debt balance exceeding the home’s market value because HECMs are non-recourse loans.
Heirs have strict post-death timelines to navigate:
- First 30 to 60 Days: The loan servicer sends a formal notice of maturity to the estate or property. Heirs must respond in writing within 60 days, stating their intention to sell the home, refinance the loan balance, or deed the property back to the lender.
- Extensions: By submitting proof of probate opening, active real estate listing contracts, or structural repair contracts, heirs can obtain formal 60-day extensions (up to a maximum total window of 12 months from the borrower’s date of death).
- Probate Court Filings: If the property was not titled in a living trust, opening probate immediately is vital. Attorneys request Full Authority under the Independent Administration of Estates Act (IAEA). Full IAEA authority enables the estate administrator to list and sell the home without waiting for lengthy court confirmations for every purchase offer.
For families navigating complex trust and probate administration issues alongside reverse mortgage liabilities, legal guidance from established elder law practices like Judd Matsunaga, Attorney at Law – Elder Law Services of California illustrates how estate planning intersects directly with home equity retention.
The table below contrasts probate administration pathways when dealing with reverse mortgage properties:
| Feature | Limited Probate Authority | Full IAEA Probate Authority | Living Trust Administration |
|---|---|---|---|
| Court Approval Required for Sale? | Yes, formal court confirmation hearing | No, notice of proposed action only | No court involvement needed |
| Average Timeline to Close Sale | 6 to 9+ Months | 2 to 4 Months | 30 to 60 Days |
| Risk of Reverse Mortgage Foreclosure | High (Servicer timelines expire) | Low (Fast execution fits extensions) | Minimal (Immediate trustee power) |
| Servicer Extension Approval Likelihood | Moderate | Very High | Very High |
Frequently Asked Questions About California Reverse Mortgages
Can heirs challenge a reverse mortgage after a parent passes away?
Yes, heirs and trust beneficiaries possess legal standing under California law to challenge a reverse mortgage executed by a deceased parent. Legal challenges typically allege financial elder abuse, lack of legal capacity, or third-party undue influence.
California imposes strict statutes of limitations—generally two to four years from the date the cause of action accrued or was reasonably discovered under the “discovery rule.” If a third party or servicer actively concealed financial elder abuse, the running of the legal deadline may be tollable until heirs uncover the records.
How long do heirs have to sell or pay off a home with a reverse mortgage?
Heirs initially receive 30 to 60 days from the borrower’s passing to communicate their intentions to the loan servicer. Upon receiving a written request along with proof of probate filing or a real estate listing agreement, servicers routinely grant initial extensions.
Servicers can approve up to two 60-day extensions, giving heirs up to 6 months—and in documented hardship or complex probate scenarios, up to a maximum of 12 months—to payoff the balance, complete a short sale, or finalize a conventional property sale.
What damages can be recovered in a California reverse mortgage fraud lawsuit?
Victims of reverse mortgage fraud or financial elder abuse can seek comprehensive compensatory and punitive damages under California civil codes:
- Full reimbursement of lost home equity and unauthorized loan fees.
- Mandatory legal fee shifting and court costs under Welfare and Institutions Code § 15657.5.
- Double or treble damages for intentional or fraudulent elder financial abuse.
- Restitution and judicial orders imposing constructive trusts over misdirected financial proceeds.
Conclusion
A reverse mortgage can serve as a beneficial financial solution when utilized under appropriate conditions. However, when deceptive advertising, financial elder abuse, or uncooperative loan servicers threaten your family’s home equity, prompt legal action is essential. Acting quickly within post-death notification windows ensures heirs preserve their rights, stop trustee sales, and clear probate hurdles effectively.
At Capital Home Mortgage California, we remain committed to helping California families understand their home financing options, navigate complex mortgage requirements, and protect their generational housing wealth. Whether you are seeking a compliant mortgage product, exploring refinance strategies to pay off an inherited debt, or reviewing our general mortgage resources on our Blog, having accurate information makes all the difference.
If you suspect financial exploitation or face an impending foreclosure sale on an inherited property, consult a certified reverse mortgage attorney in California immediately. To explore flexible forward loan solutions or discuss paying off an existing HECM line, visit Golden State Mortgage Home today to connect with our dedicated home loan specialists.


