
Why the $25,000 First Home Buyer Grant Matters Right Now
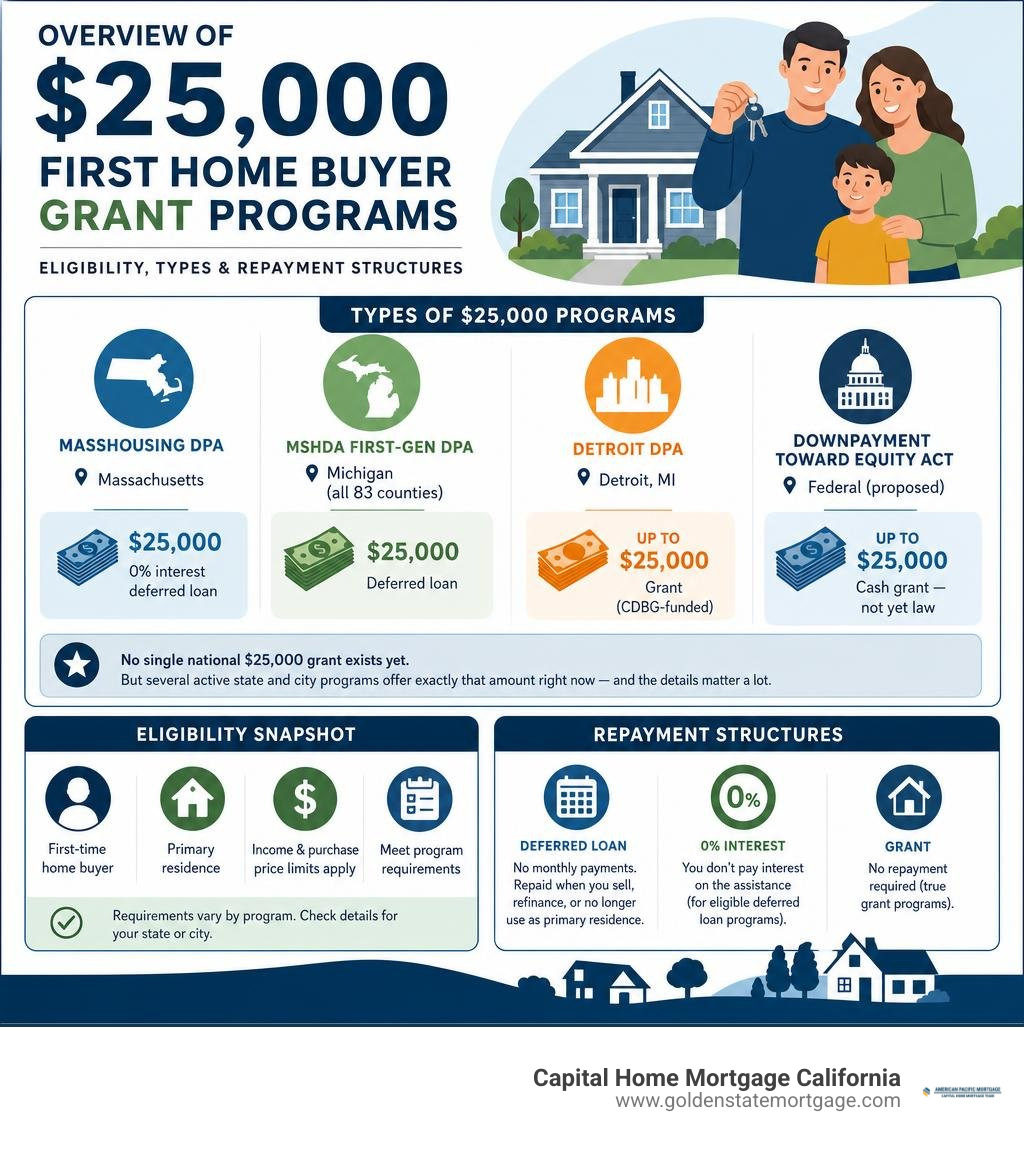
If you’re researching a $25,000 grant for first home buyers, here’s what you need to know upfront:
| Program | Location | Amount | Type |
|---|---|---|---|
| MassHousing DPA | Massachusetts | $25,000 | 0% interest deferred loan |
| MSHDA First-Gen DPA | Michigan (all 83 counties) | $25,000 | Deferred loan |
| Detroit DPA | Detroit, MI | Up to $25,000 | Grant (CDBG-funded) |
| Downpayment Toward Equity Act | Federal (proposed) | Up to $25,000 | Cash grant — not yet law |
No single national $25,000 grant exists yet. But several active state and city programs offer exactly that amount right now — and the details matter a lot.
Saving for a down payment is the single biggest obstacle most families face when trying to buy their first home. Even in markets where buyers qualify for a mortgage on paper, coming up with $15,000 to $30,000 upfront — before moving costs, inspections, or reserves — stops millions of people cold every year.
That’s exactly the gap these programs are designed to fill. Whether it’s a 0% interest deferred loan from a state housing authority, a city-backed grant funded by federal block grants, or a proposed federal bill still working through Congress, the landscape of $25,000 first-home buyer assistance is both promising and — let’s be honest — a little confusing.
This guide cuts through the noise.
I’m Dale Gremillion, Senior Loan Officer and Producing Branch Manager at Capital Home Mortgage California, with over 25 years of experience helping buyers navigate down payment assistance options — including programs comparable to the $25,000 grant for first home buyers covered here. I’ll walk you through exactly what’s available, who qualifies, and how to put it to work alongside the right primary mortgage.
Overview of the 25000 Grant for First Home Buyers

When people search for a 25000 grant for first home buyers, they are usually looking for one of three distinct financial tools: a true forgivable cash grant, a zero-percent interest deferred second mortgage, or an amortizing low-interest loan. Understanding how these tools work is crucial before you start writing offers on properties.
A true cash grant is funds provided directly at closing that never need to be paid back, assuming you meet basic occupancy criteria. City-level initiatives—such as municipal Community Development Block Grant (CDBG) initiatives—frequently structure their funds this way.
On the other hand, many state housing finance agencies structure their $25,000 programs as 0% interest deferred second loans. Under this structure, no monthly payments are added to your budget. The $25,000 principal simply sits quietly in the background until you sell the property, refinance your primary mortgage, or pay off the home loan in full.
Here is how these common financial assistance models compare side by side:
| DPA Program Type | Monthly Payment | Interest Rate | Repayment Trigger | Best For |
|---|---|---|---|---|
| Forgivable Cash Grant | $0 | 0% | Forgiven after set occupancy (e.g., 5 years) | Maximum upfront savings with no future debt |
| 0% Deferred Second Loan | $0 | 0% | Paid back upon sale, refinance, or mortgage payoff | Buyers keeping monthly housing costs as low as possible |
| 15-Year Amortizing Loan | Low fixed monthly fee | 2% – 3% APR | Paid monthly over 180 months | Buyers looking to build second-mortgage equity steadily |
To stay informed about proposed federal changes, read up on What Is the $25,000 Down Payment Toward Equity Act? | 2026 to understand where national legislation currently stands.
Approved Spending for the 25000 Grant for First Home Buyers
You cannot simply take $25,000 in assistance and buy new living room furniture or fund a victory vacation after closing. Public housing assistance funds come with strict spending rules designed to make your mortgage sustainable.
Eligible funds can generally be applied toward:
- Minimum Down Payment Requirements: Satisfying the 3.5% minimum required for FHA home loans or the 3% required for conventional first-time buyer mortgages.
- Closing Costs: Covering necessary transaction costs including escrow services, lender underwriting, title insurance, home inspections, and appraisal fees.
- Prepaid Items: Pre-funding property tax escrow accounts, homeowners insurance premiums, and daily interest charges.
- Interest Rate Buydowns: Paying discount points upfront to secure a lower permanent interest rate, significantly lowering your monthly mortgage payment for the life of the loan.
To calculate how interest rates directly impact your monthly payments, review our current Rate Assumptions.
Repayment Terms, Forgiveness, and Occupancy
Understanding the fine print prevents expensive surprises down the road. Most down payment assistance (DPA) programs mandate a primary residence occupancy requirement. Program guidelines require you to move into the home within 60 days of closing and maintain it as your principal residence.
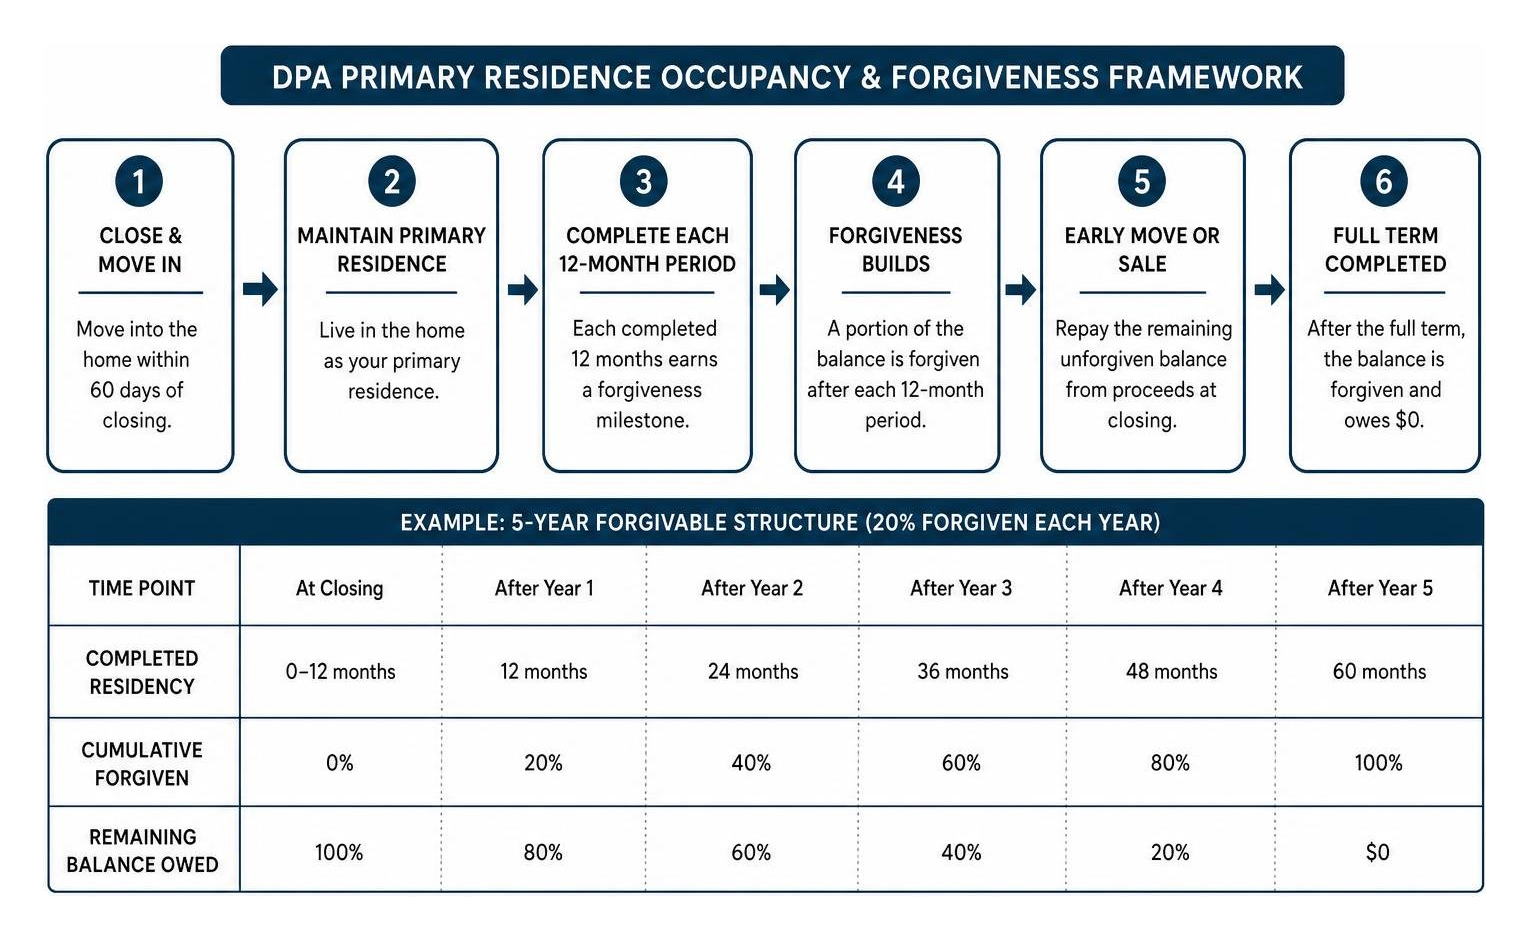
Forgivable structures typically scale down your repayment obligations each year you reside in the home. For example, under a 5-year forgivable timeline, 20% of the loan is forgiven for each completed 12-month residency cycle. Stay in the home for full five years, and the repayment balance drops to $0. If you sell or move out after year three, you repay only the remaining unforgiven portion from your proceeds at closing.
Eligibility Criteria for First-Time and First-Generation Buyers
Qualifying for a 25000 grant for first home buyers requires meeting programmatic criteria established by the issuing agency. While guidelines vary by municipality and state, most base eligibility on income caps, homebuyer history, and financial stability.
Income qualification is calculated using Area Median Income (AMI) thresholds set annually by HUD. Program caps typically fall into three brackets:
- 80% AMI Limit: Standard for city-level grants funded via municipal CDBG programs, targeting modest-income households.
- 120% AMI Limit: Standard limit for most state-backed programs and proposed federal legislation.
- 135% AMI Limit: Expanded income thresholds used in high-cost housing markets to assist middle-income working families.
For context, in higher-cost areas, 135% AMI caps can allow household income limits up to $205,335, whereas lower-cost counties may cap qualification closer to $129,870.
First-Generation Homebuyer Rules
A growing number of down payment initiatives now specifically target first-generation homebuyers. This criterion is designed to bridge generational wealth gaps by offering aid to families without access to intergenerational home equity transfers.
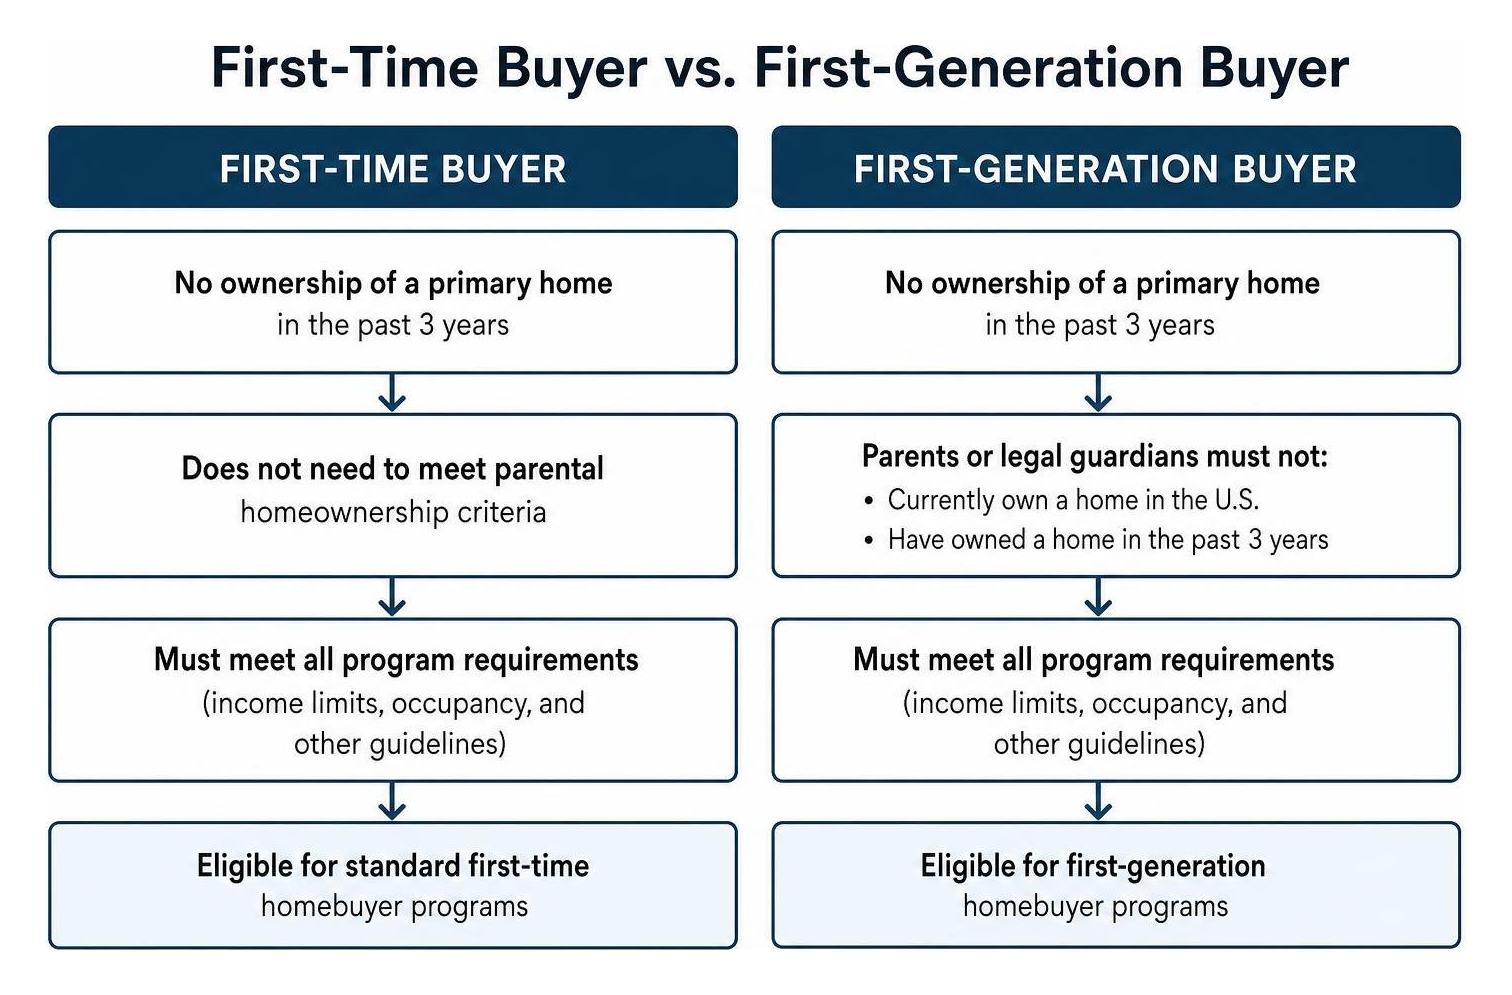
To qualify as a first-generation homebuyer under most state and federal guidelines:
- You must meet standard first-time homebuyer rules (no primary homeownership in the past 3 years).
- Your parents or legal guardians must not currently own a home in the United States, nor have owned a home within the preceding 3-year lookback window.
- If you were raised in foster care, you automatically qualify as a first-generation homebuyer regardless of biological parental status.
Property Price Caps and Credit Requirements
Free money still comes with financial guardrails. To keep assistance focused on affordable housing, programs institute maximum property purchase price caps and credit underwriting standards.
Most assistance programs mandate a minimum credit score of 640, though pairing DPA with specific FHA primary loans can sometimes allow for flexibility depending on total credit health and debt-to-income (DTI) ratios (typically capped at 45% to 50%).
Eligible property types generally include:
- Single-family detached homes
- Approved townhomes and condominiums
- Multi-unit residential properties (2 to 4 units), provided you occupy one unit as your primary residence
- Manufactured housing permanently affixed to real estate. To explore how manufactured homes provide affordable entry points, read our guide on California Manufactured Homes Advantages.
State, Municipal, and Federal $25,000 Program Comparison
Because down payment assistance is decentralized, where you live determines what you can access. Let’s look at how active regional $25,000 programs compare across the country:
- Massachusetts MassHousing Expansion: MassHousing converted prior 15-year amortizing second loans into a 0% deferred $25,000 DPA program. Since early 2023, MassHousing delivered over $1.9 billion in mortgage financing, assisting over 5,900 households and issuing 4,757 DPA loans.
- Michigan MSHDA First-Gen Pilot: Backed by $8 million in state budget appropriations, MSHDA offers a $25,000 deferred loan across all 83 counties specifically for first-generation buyers with credit scores of 640+ purchasing homes under $224,500.
- City of Detroit DPA: Backed by $9 million in CDBG and CDBG-DR funds, Detroit offers up to $25,000 in direct assistance for buyers under 80% AMI who have lived in the city for at least 12 months, giving processing priority to residents impacted by severe flooding events.
- International Comparisons: Programs abroad offer similar structural incentives. For example, buyers exploring Australian state programs can review the First Home Owner (New Homes) Grant | Revenue NSW to see how NSW delivers $10,000 grants on new construction capped under $600,000.
Current Status of Federal $25,000 Legislative Proposals
The proposed federal Downpayment Toward Equity Act (originally introduced as H.R. 4495) generated massive national interest by proposing up to $25,000 in cash grants for first-time, first-generation homebuyers.
However, as of 2026, this bill has not passed Congress and is not active law.
The bill remains stalled in legislative committees. Housing policy analysts consider it unlikely to pass under current congressional dynamics. Prospective buyers should not put their homeownership plans on hold waiting for federal legislation. Instead, focus on active state, county, and municipal programs that are fully funded and open for applications today.
Combining State Grants with Local Assistance
One of the best strategies for maximizing buying power is program stacking—combining multiple assistance programs on a single purchase transaction.
When stacking programs, work with an experienced lender who understands secondary financing guidelines. Primary mortgage programs (such as FHA or Conventional loans) place limits on combined loan-to-value ratios and secondary financing liens.
To see how municipal programs function locally, check out Santa Ana Down Payment Assistance Programs for detailed examples of city-level assistance stacking.
Application Steps and Required Documentation
Applying for a 25000 grant for first home buyers is integrated directly into your primary mortgage approval process. You do not apply directly to government agencies; instead, you work through an approved partner lender authorized to originate and service state housing agency loans.
How to Apply for a 25000 Grant for First Home Buyers
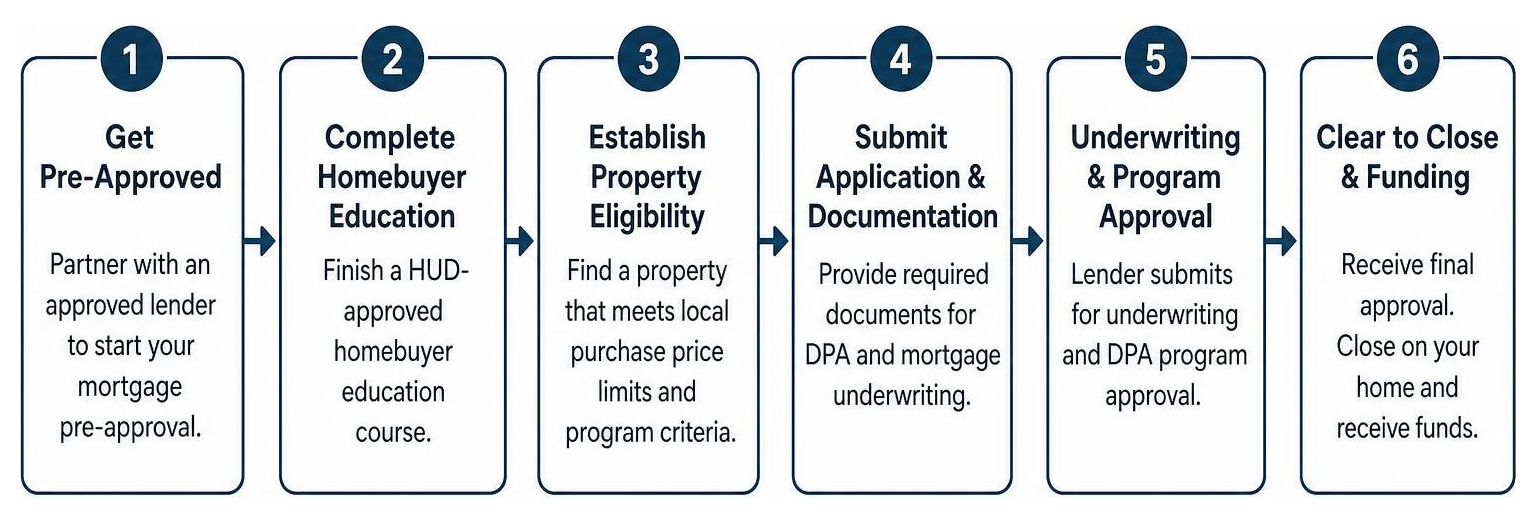
Follow this step-by-step roadmap to secure your assistance without delays:
- Get Pre-Approved with an Approved Lender: Partner with a direct mortgage lender authorized to process local down payment assistance loans.
- Complete HUD-Approved Homebuyer Education: Almost all DPA programs require completing an online or in-person financial counseling class certified by HUD.
- Establish Property Eligibility: Find a property that meets local purchase price limits and meets underwriting inspection standards.
- Lock Your Primary Mortgage & Reserve DPA Funds: Your lender submits your loan file to reserve down payment assistance funds before program allocations run out.
- Underwriting & Closing: Submit income documentation for dual underwriting—verifying eligibility for both your main mortgage loan and the assistance program.
California buyers looking for regional options can review official guidelines through the MyHome Assistance Program – Homebuyers – CalHFA – CA.gov.
Essential Documents Needed for DPA Approval
Having your documentation organized speeds up processing times significantly. Keep digital copies of the following essential documents ready:
- Income Verification: Past 30 days of consecutive pay stubs and documentation for all household income sources.
- Tax Documentation: Signed federal tax returns (Form 1040) and W-2/1099 statements for the past 2 to 3 consecutive tax years.
- Asset Statements: Two months of complete bank statements for all checking, savings, and investment accounts.
- Identification & Residency Proof: Valid government-issued photo ID, Social Security card, and municipal utility bills or lease agreements proving local residency history.
- Education Certificate: Completion certificate from a HUD-certified homebuyer education provider.
Frequently Asked Questions About Down Payment Assistance
Has the federal $25,000 down payment grant passed into law?
No. The Downpayment Toward Equity Act remains a proposed congressional bill and has not been enacted into law as of 2026. Buyers looking for $25,000 assistance should focus on active state housing finance authority programs and municipal city grants currently open for applications.
What is the difference between a first-time and a first-generation homebuyer?
A first-time homebuyer is defined as someone who has not owned a primary residence within the last 3 years. A first-generation homebuyer meets the first-time buyer rule and has parents or legal guardians who do not currently own a home in the U.S. and have not owned one in the past 3 years.
Can down payment assistance be used on a condo or multi-family unit?
Yes! Most state and city $25,000 DPA programs allow you to purchase single-family homes, HUD-approved condominiums, townhomes, and multi-unit residential properties (up to 4 units), provided you live in one of the units as your primary residence.
Conclusion
Finding and securing a $25,000 grant for first home buyers comes down to knowing which active state and municipal programs exist in your market—and pairing them with the right primary mortgage loan. While national headlines often focus on stalled federal proposals, actionable down payment assistance programs are delivering real cash at closing right now.
At Capital Home Mortgage California, we specialize in guiding first-time buyers through every step of the mortgage financing process. As a direct mortgage lender with in-house processing, we deliver fast, on-time closings tailored to your specific financial situation. From low down payment FHA and VA loans to specialized state down payment assistance programs, our team provides personalized 7-day-a-week support.
Ready to take the next step toward owning your first home? Explore our educational resources on our Blog or learn how to leverage local programs today when you Explore Local Down Payment Assistance Programs. Let’s make your dream of homeownership a reality!


